All Posts
6 min read
Commercial Mortgage Loan Broker: A Modern Guide for Business Owners and Property Investors
Published on 3 November 2026
Buying or refinancing commercial property in the UK involves manual underwriting, dozens of lender policies, and documentation requirements that differ from anything in the residential market. A commercial mortgage loan broker cuts through that complexity. This guide explains what brokers do, how they work, what lenders look for, and how technology is changing deal origination for the better.
Quick overview: what a commercial mortgage loan broker does
A commercial mortgage loan is a form of commercial lending secured against business property such as offices, warehouses, retail units, semi commercial buildings, or mixed use properties. Unlike a standard unsecured business loan, the lender takes a legal charge over the property. Unlike a residential property mortgage, the lending decision relies on rental income, tenant quality, or the borrower's trading profits rather than personal salary.
A commercial mortgage loan broker acts as an intermediary between borrowers and lenders. Brokers specialise in complex financing for income-producing properties and maintain relationships with a wide network of lenders: high-street banks, challenger banks, specialist lenders, and alternative finance providers. An extensive lender network increases the chances of securing competitive financing because each lender has different eligibility criteria for sector, region, lease terms, and borrower profile.
Commercial finance brokers simplify the loan application process. Here is what they do in practice:
- Compare commercial mortgage rates across multiple lenders so you see the best deal available for your situation, not just the first offer from a single bank.
- Explain arrangement fee structures, interest rate types (fixed rates vs variable), and covenants in plain language.
- Package your financial data to meet each lender's underwriting criteria, improving approval chances.
- Connect businesses with tailored funding solutions across commercial mortgages, bridging finance, development finance, and other property finance products.
- Save weeks of back-and-forth by managing paperwork, valuations, and solicitor coordination.
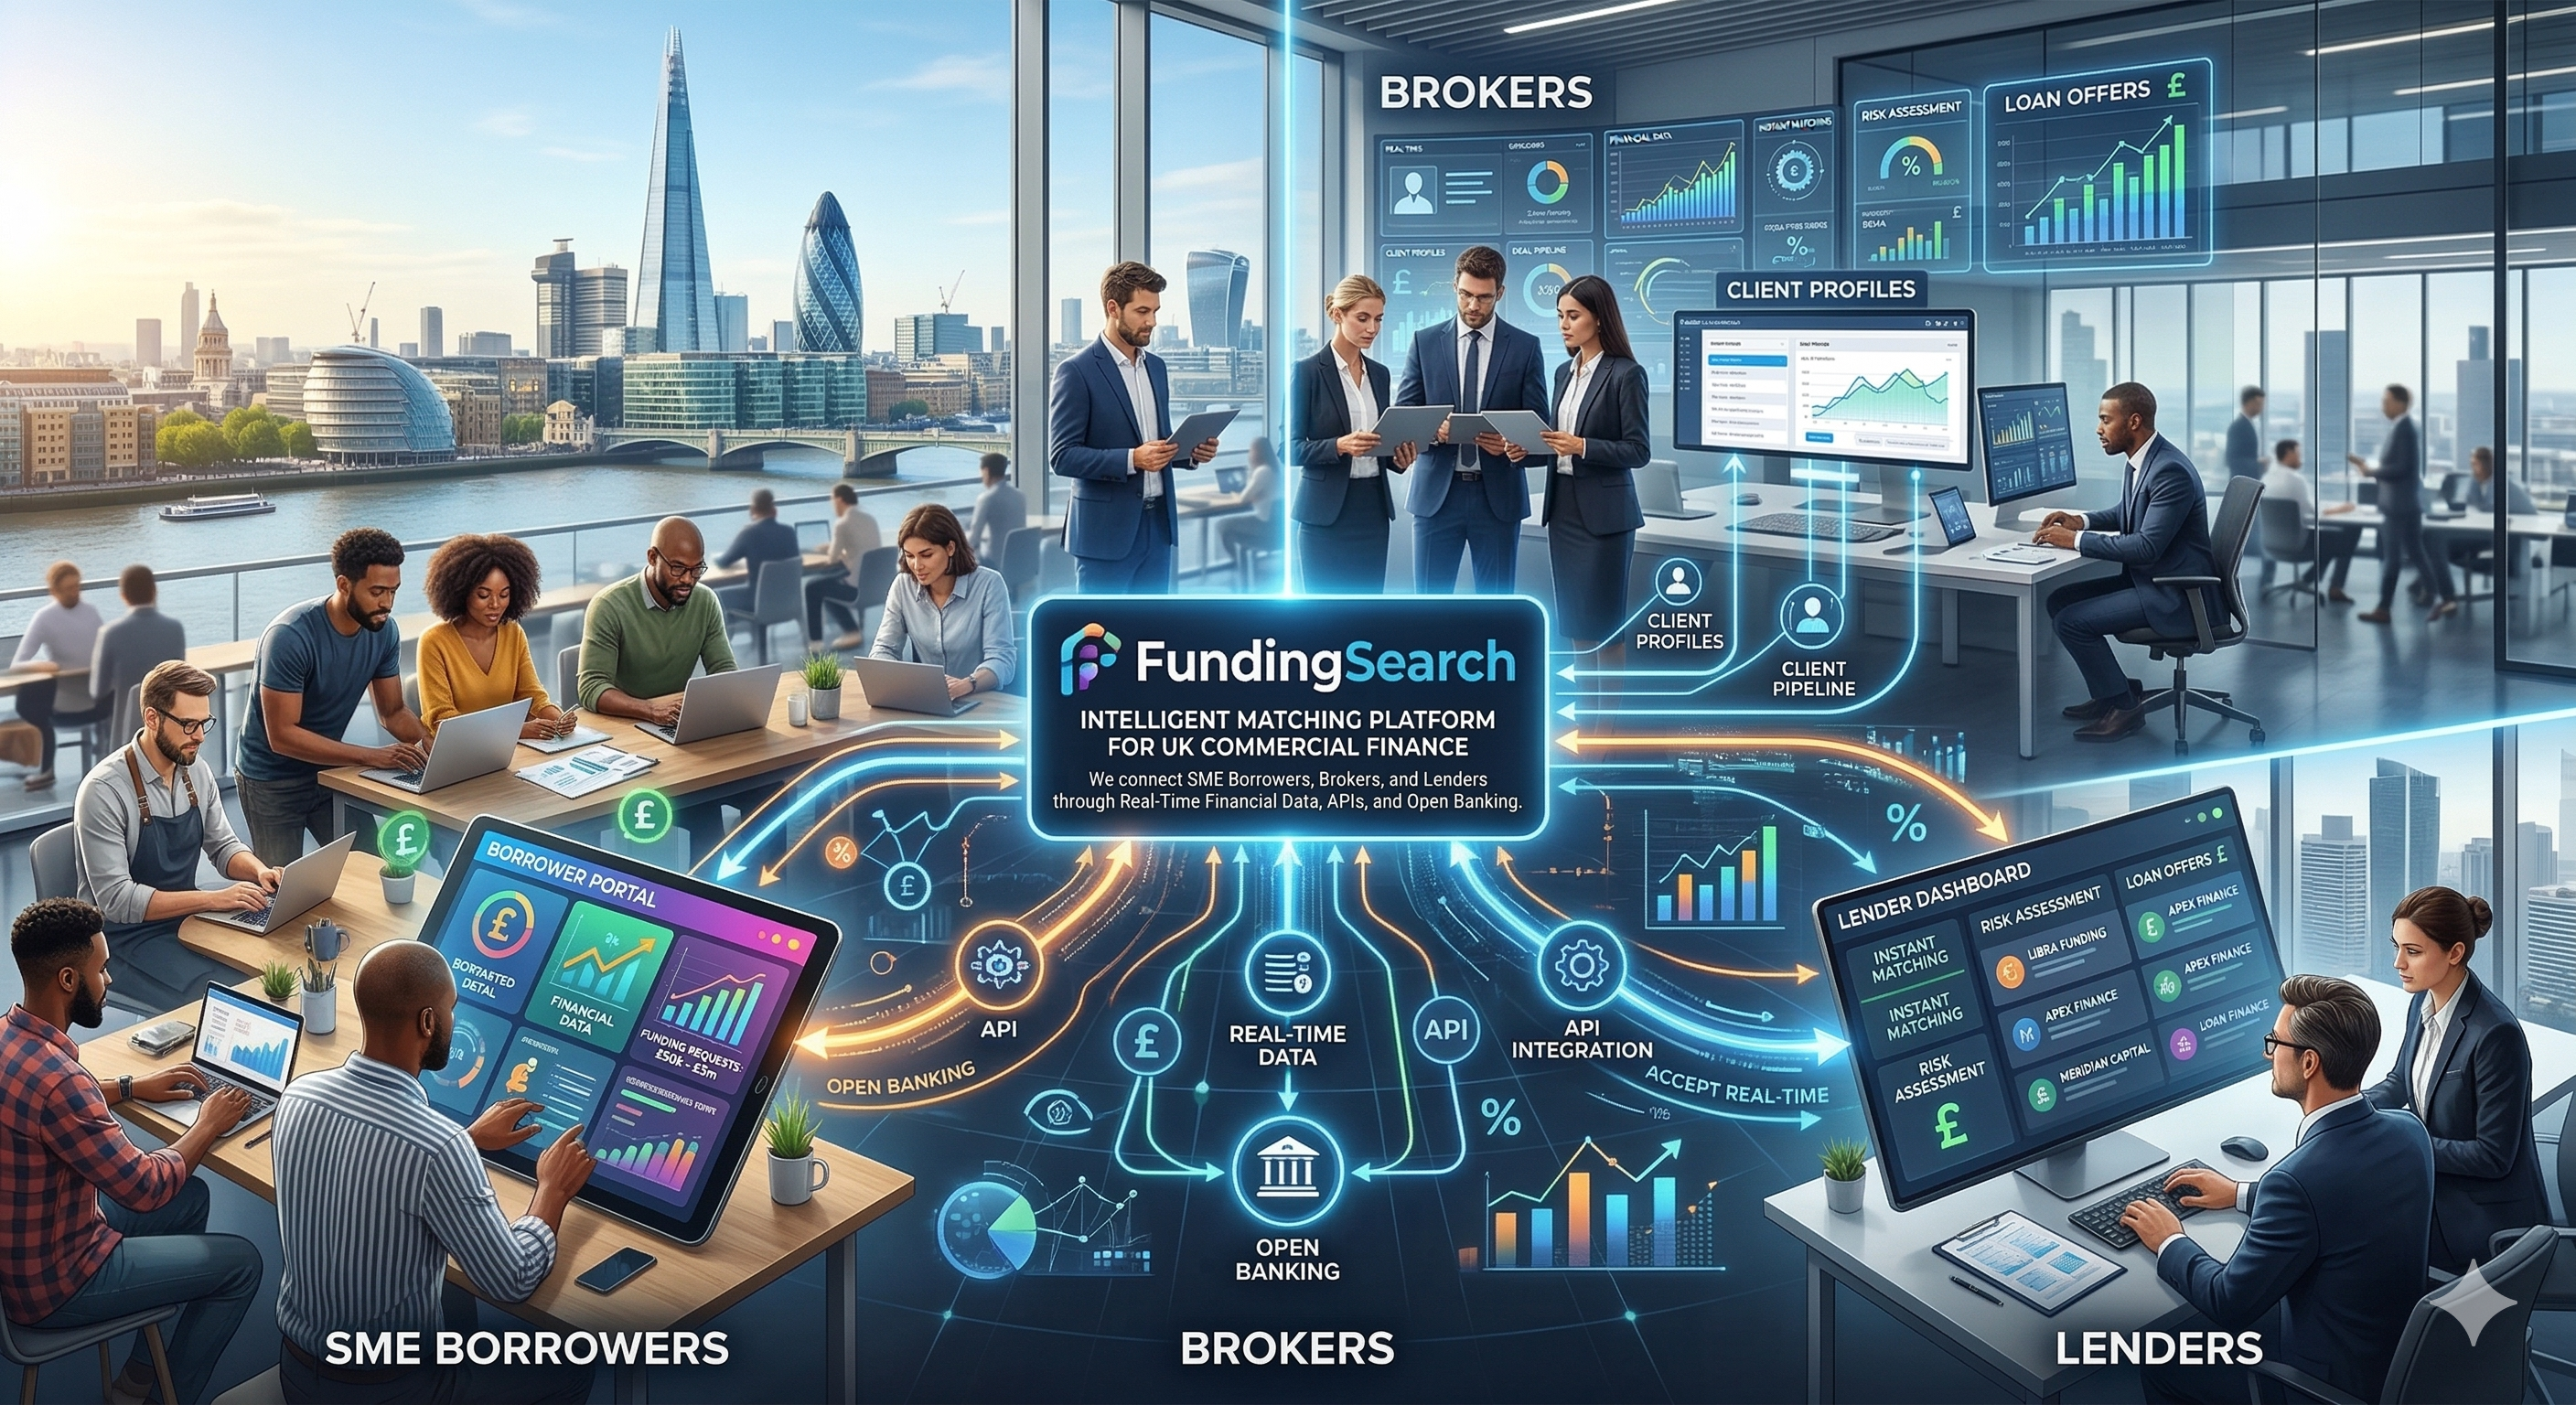
- Use platforms like FundingSearch to match borrowers with suitable lenders using AI-driven algorithms and verified financial data from Xero, Sage, and Companies House.
What is a commercial mortgage loan (and when you should use one)?
A commercial mortgage is a secured loan and a form of commercial lending used to purchase, refinance, or release equity from a non-residential or mixed-use property. It differs from a residential property mortgage in two ways: the property is non-residential or mixed-use, and the application process requires detailed financial assessments compared to residential loans. Commercial mortgages typically have higher interest rates than residential mortgages because lender risk on business property is greater.
Common use cases include:
- An SME buying its own business premises, such as a warehouse or workshop, to stop paying rent and build equity.
- Property investors acquiring commercial units or mixed use properties with flats above shops.
- Landlords expanding an existing portfolio of buy to let commercial assets.
- Business owners using a commercial mortgage to refinance existing property debt at lower rates or to raise additional funds for expansion.
Key facts about commercial mortgages in the UK market:
- You can borrow from £50,000 to £50 million for commercial properties, depending on the lender and asset.
- Loan to value ratios range from 60% to 75% for investment property; owner-occupier deals reach 75% to 80% in certain circumstances.
- Loan terms run from 5 to 25 years, with some lenders offering up to 30 years.
- Commercial mortgages typically have variable interest rates, though fixed rates are available for set periods (often 2, 3, or 5 years).
- Commercial mortgages can finance properties for business purposes, including offices, retail, industrial, leisure, and medical premises.
- Buy to let mortgages on commercial property are assessed on rental income and tenant covenant strength; owner-occupied commercial property loans rely on the business's trading income and cash flow, and some deals use interest-only commercial mortgage structures.
- Repayments may lead to property repossession if not maintained, so lenders stress-test affordability before approval.
A commercial mortgage sits alongside other business finance options. Many SMEs hold a commercial property mortgage on their premises while using asset finance for equipment and invoice finance against unpaid invoices to support working capital.
The specialist role of a commercial mortgage loan broker
Commercial mortgage underwriting is manually processed. Each lender sets its own lending criteria for sector, location, lease length, tenant strength, EPC rating, and borrower credit history. A commercial finance broker navigates this landscape in real time, knowing which lenders are actively lending in a given asset class and which have tightened their policies.
Brokers use a consultative approach to evaluate overall financial health. On the property side, they assess yield, lease terms, tenant covenant, EPC compliance, and location. On the borrower side, they review trading history, company structure (limited company, LLP, or SPV), directors' credit score, and financial statements. This dual analysis is what makes commercial mortgage applications more involved than residential ones.
- Brokers help businesses navigate complex lending criteria and financing challenges, whether the issue is a short unexpired lease, a newly incorporated SPV, or non-standard income from a professional practice.
- They can optimise loan pricing by understanding current market conditions; for example, knowing that one lender prices industrial assets 50 basis points cheaper than another for the same loan to value.
- Brokers should have experience with specific property types and business financial structures. A broker placing a hotel deal needs different lender relationships than one placing a multi-let industrial estate.
- Through platforms like FundingSearch, brokers now use AI matching algorithms and open finance data (Xero, Sage, Companies House) to pre-qualify applicants. FundingSearch reports reducing lender due diligence time by about 60% through verified data integration.
- Brokers introduce complementary financial products where appropriate: development finance for conversions, commercial bridging finance for auction purchases, asset finance for equipment, or invoice finance for cash flow gaps.
Types of commercial properties and scenarios brokers can finance
Brokers arrange commercial property loans across a broad range of UK assets as part of wider commercial lending for business and investment property. Funding appetite and pricing vary depending on property type, lease profile, tenant strength, and location.
- Standard commercial property categories: offices, high-street retail, industrial units, warehouses, logistics hubs, medical centres, leisure venues (gyms, restaurants), and hotels.
- Specialist and alternative assets: care homes, student accommodation, serviced offices, HMOs within mixed portfolios, and land with or without planning permission for development finance.
- Semi commercial and mixed use properties: shops with residential flats above. Lenders require clear floor-area splits between the commercial and residential portions, and lending criteria differ from pure commercial deals.
- Lease profile matters: a modern industrial unit with a 15-year FRI lease to a national tenant attracts higher loan to value and lower rates than a short-lease ground-floor retail unit in a secondary town with an independent tenant.
- Commercial financing includes products like short-term bridging loans and investment mortgages, so brokers can help identify suitable finance options for businesses across the risk spectrum.
- Some brokers focus on niches (semi commercial mortgages, buy to let, refurbishment projects), while others use technology like FundingSearch for broader coverage across all property types.
How a commercial mortgage broker process works (step-by-step)
The journey from first conversation to completion typically runs 6 to 16 weeks, depending on deal complexity. Here is how it works:
Discovery. The broker gathers basic information about the business, the commercial premises, existing borrowings, intended use, and objectives (purchase, refinance, equity release, development). Brokers manage the entire application process from paperwork to final approval.
Data verification. Modern brokers pull filed accounts from Companies House and connect to the borrower's accounting software (Xero or Sage) via platforms like FundingSearch to access a broader network of alternative lenders. This gives lenders verified trading history and management accounts, reducing queries later.
Lender selection. The broker maps your deal against lender panels. Published criteria show maximum LTVs from 55% to 80% and interest cover ratios from 1.20x to 1.65x, depending on the lender. Professional brokers avoid applying to multiple lenders simultaneously to protect credit profiles; they select the right person at the right lender for each case.
Options presentation. The broker presents recommended lenders, estimated commercial mortgage rates (fixed rates or variable), arrangement fee levels, monthly payment projections, required security, and loan terms so you can compare.
Application and underwriting. Brokers package loan submission materials to appeal to lenders' underwriting criteria. Documents include filed accounts, bank statements, lease agreements, tenancy schedules, ID/AML checks, and a property valuation. Brokers assist in managing legal and appraisal requirements during this stage.
Completion and review. Brokers liaise with solicitors and valuers, confirm conditions precedent (insurance, title, lease registration), and ensure drawdown proceeds smoothly. Post-completion, they review the commercial mortgage at break dates or when rates shift to confirm you still have competitive rates.
Key criteria lenders assess on a commercial mortgage loan
Understanding lender criteria upfront is where choosing the right commercial broker can influence loan terms and costs. Here is what lenders examine:
Borrower-focused criteria:
- Company structure: limited company, LLP, or SPV. Many lenders require a minimum 3-year trading history; some accept 12 months plus projections.
- Directors' credit history and personal credit score.
- Quality of financial statements and evidence of stable cash flow.
Deal-focused criteria:
- Purchase price versus independent valuation; requested loan amount and loan to value ratio.
- It is important for brokers to understand how lenders assess Debt Service Coverage Ratios. Typical requirements range from 1.20x to 1.65x. MT Finance, for example, requires an interest cover ratio of 125% on both 2-year and 5-year fixed rates.
- Sensitivity testing against interest rate rises; most lenders apply a stress buffer above the pay rate.
Property-focused criteria:
- Type of commercial property, lease length and break clauses, void risk assumptions, tenant covenant strength.
- Location: London and regional city centres attract more lenders than tertiary high streets.
- EPC rating: some lenders now require EPC C or better for offices.
For semi commercial and mixed use properties, lenders look at the proportion of residential versus commercial income and whether the residential element triggers any regulated lending obligations under the Prudential Regulation Authority.
Brokers using platforms like FundingSearch quickly exclude lenders whose policies will not fit, preventing unnecessary declines and protecting the borrower's credit profile.
Commercial mortgage vs other business finance options
A commercial property mortgage is one piece of the wider specialist finance landscape. Each product serves a different purpose.
- Unsecured business loan: faster to arrange, no property security needed, but higher interest rate and shorter repayment terms (typically 1 to 5 years). Suitable for smaller funding options where speed matters more than cost.
- Bridging loan: designed for fast acquisitions, auction purchases, or refurbishment projects before refinancing onto a longer-term commercial mortgage. Terms up to 12 months; rates higher than term lending.
- Development finance: staged drawdowns for ground-up builds or office-to-residential conversions. Lenders monitor progress via surveyors. Interest is often rolled up into the loan, and specialist bridging loan brokers and lenders can help structure short-term funding ahead of term finance.
- Asset finance: funds equipment, vehicles, or machinery. Preserves working capital. Not secured on real property. Brokers increasingly rely on commercial finance broker software to manage these multi-product pipelines efficiently.
- Invoice finance: releases cash tied up in unpaid invoices. Provides flexible funding for day-to-day operations.
Brokers who use origination platforms can place clients across multiple products at once; a commercial mortgage for new premises, asset finance for a fit-out, and invoice finance for cash flow; creating a balanced capital structure rather than forcing everything into a single property-backed loan.
Digital deal origination: how FundingSearch helps commercial mortgage brokers
FundingSearch is a UK fintech marketplace founded in 2025 in Sheffield. It covers seven commercial finance asset classes: business loans, commercial mortgages, bridging finance, invoice finance, asset finance, asset-based lending, and trade finance. Brokers manage whole-of-market needs in one place rather than juggling separate lender portals.
The platform's AI-driven matching engine uses verified financial data (Companies House, Xero, Sage) and deal parameters (loan to value, sector, region, security type) to identify suitable lenders within seconds. This reduces time spent on manual research, avoids sending deals to mainstream lenders who will decline, and increases approval rates.
Workflow tools handle centralised document collection, status tracking, and communication between broker, borrower, and lender. FundingSearch operates on a B2B SaaS subscription model for brokers and lenders. SMEs access matching either free or at low cost through their broker, keeping long term relationships between broker and client front and centre.
Professional advisers, including accountants, can use FundingSearch to add a scalable, technology-backed funding referral service. If you are a broker looking for the right funding tools, compare commercial finance broker platforms to see how FundingSearch fits, and review independent guides to the best loan origination software platforms.
Working with a commercial mortgage broker: costs, compliance and what to ask
Unlike standard consumer mortgages, many commercial property loans are unregulated in the UK. Transparency matters when choosing a broker.
- Commercial mortgage brokers typically earn through broker fees or lender commissions. Common models include fixed fees (£1,000 to £5,000), percentage-based fees on loan amount (1% to 2%), or lender-paid procuration fees (Aldermore, for example, includes a 1.5% broker procuration fee drawn from the arrangement fee). Get clear written disclosure before proceeding.
- A reliable broker should provide clear and transparent communication throughout the process. Ask: which lenders do they work with? Do they have experience in your sector and property type? Do they use marketplace technology like FundingSearch? How will they present your case?
- Check for membership of relevant UK trade bodies such as NACFB. Confirm how complaints would be handled.
- Good brokers use their connections to negotiate competitive financing terms, including arrangement fee reductions and covenant flexibility, on behalf of existing customers and new clients alike.
- For larger or complex portfolios (multi-property business property holdings or semi commercial portfolios), a broker using data-driven origination software provides faster, more accurate lender selection than one relying on phone calls alone.
Is now the right time to explore a commercial mortgage loan?
Interest rates, yields, and valuations shift constantly. Fixed rates for owner-occupier commercial mortgages start around 5.5% in late 2026; investment property deals price closer to 6.0% to 9.0%, and rates vary depending on risk profile and lender appetite.
- Common triggers for speaking to a broker: lease expiry on rented business premises, an opportunity to buy an existing property you occupy, refinancing an older commercial mortgage coming off a fixed rate, or releasing equity to secure funding for expansion.
- Early engagement gives you time to tidy accounts, improve your credit score, and prepare documents. That preparation improves lender appetite and can lower your monthly payment.
- Using a digital marketplace like FundingSearch through a broker provides an early, data-backed view of indicative lender appetite across commercial mortgage, development finance, and other financial solutions.
- Before your first broker conversation, prepare basic information: latest filed accounts, management figures from Xero or Sage, property details (address, tenure, lease terms remaining), and a schedule of existing debts. This accelerates the application process and helps the broker find the right solution faster.