All Posts
5 min read
Open Banking for SME Lenders: How Open Banking is Changing SME Lending
Published on 4 November 2026
A guide to APIs, data standards, and the future of creditworthiness assessment
The UK SME lending market is undergoing a quiet revolution. Not through flashy fintech startups or blockchain hype, but through something more fundamental: open banking.
For decades, lenders have assessed SME creditworthiness using limited, outdated data. Bank statements. Tax returns. A handful of financial ratios. Alternative lenders have tried to work around this by relying on workarounds: merchant data, ad hoc API connections, self-reported figures that don't reflect reality.
Open banking changes this fundamentally. For the first time, lenders can access verified financial data in real time, directly from accounting systems and banks. APIs have moved from niche integration to industry standard. Data standards have created a common language across platforms.
This is how creditworthiness assessment is being reinvented.
What is Open Banking, and Why Does It Matter?
Regulatory Background
Open banking is a regulatory initiative that enables the secure sharing of customer financial data between different institutions. In the UK, the Open Banking Standard was introduced through PSD2 (Payment Services Directive 2) and continues to evolve through the FCA's Open Finance roadmap.
Customer Consent Process
Put simply: a customer can grant permission for a fintech platform, lender, or broker to access their financial data directly from their bank or accounting software. No manual downloads. No PDFs. No delay.
Impact on SME Lending
The impact has been profound. Over 750,000 SMEs in the UK now use open banking products for cash management, forecasting, and finance applications. The shift is accelerating.
For lending, this matters because creditworthiness assessment has always been hampered by data quality and currency. Open banking solves both problems at once.
An API (Application Programming Interface) is simply a standardised way for software systems to talk to each other. In SME lending, APIs allow lenders to pull data automatically from accounting systems like Xero and Sage, and from banking platforms.
This might seem technical, but the practical implications are enormous.
Real-Time Financial Data
Traditional Data Challenges
Traditional lending relied on audited accounts and other historic data rather than up to date information: historical snapshots, often 6-18 months old. By the time a lender saw the data, business conditions had likely changed significantly.
API-Driven Assessment
APIs enable real-time access to live P&L, balance sheet, and cash flow information. A lender can now assess the business as it exists today, not as it existed last year. With consent, business transaction data and transaction history can strengthen credit analysis and help lenders evaluate thin-file or non-traditional businesses more fairly.
This transforms speed and accuracy in equal measure. Alternative credit scoring models can also use fine-grained current behaviour instead of older records.
Elimination of Manual Data Entry
Benefits for Brokers and Lenders
Brokers spend hours manually entering figures from accounts into application forms, and uploading bank statements is the manual, time consuming alternative this process replaces. Errors creep in. Data gets misaligned. Lenders then spend more hours verifying and cross-checking.
APIs eliminate this entirely. Financial data flows directly from the source system into the lender's underwriting platform, making loan applications faster and reducing friction for business owners. No retyping. No transcription errors. No delays.
One of our broker partners recently told us that our integrated Xero pipeline saved them 12 hours per deal, purely on data entry and verification.
Auditable & Compliant Data
Regulatory Compliance Advantages
When data is sourced via API from verified systems, there's an unbroken audit trail. Regulators can see exactly where figures came from. No disputes about whether a bank statement is ‘real.'
This compliance benefit has become increasingly valuable as lenders face tighter regulations around affordability and creditworthiness assessment.
Data Standards: Creating a Common Language
The Role of Data Standards
APIs are only as useful as the data flowing through them. If Xero sends data in one format and Sage in another, and banks in a third, lenders face a chaos of interpretation.
This is why data standards matter enormously.
The UK has adopted the Open Banking Standard, which defines exactly how financial data should be structured, labelled, and transmitted. A merchant's trading history looks the same whether it comes from Barclays or NatWest. A P&L statement has consistent line items across providers.
Benefits of Standardisation
With standardised data, lenders can build algorithms that work across multiple providers. They can automate creditworthiness assessments. They can identify patterns and risk factors with confidence.
The alternative: proprietary data formats. Each integration becomes a one-off engineering effort. It's expensive. It scales poorly. It's essentially where we were before open banking.
| Data Element | Without Standards | With Standards |
|---|---|---|
| Transactions | Manual extraction, format varies by bank | Standardised transaction schema, API delivery |
| P&L | Custom formats, manual interpretation | Consistent line items, automated ingestion |
| Assertions & Metadata | Ambiguous, relies on context | Clear definitions, verifiable source |
How Alternative Lenders Are Using This to Assess Creditworthiness
Alternative Lender Types
Alternative lenders include specialist finance houses, peer-to-peer platforms, and invoice finance providers. Across the wider lending landscape, fintech-led SME lending and open banking is helping them move faster than traditional banks while making decisions with less friction, more transparency, and better data.
Advantages of Open Banking for Lenders
Open banking and APIs are giving them the tools to do this responsibly. Access to current credit data offers powerful advantages over historic data for potential lenders. Real-time insights can help reduce defaults and fraud in credit decisioning.
Cash Flow Visibility
For invoice finance and working capital providers, the critical question is always: can this business service the debt? Open banking lets them see real-time cash in and cash out, alongside broader indicators of financial health. That improves accessing credit for businesses whose recent performance has strengthened, because lenders can assess liquidity trends without relying on forecasts or old bank statements. This is why open banking matters in lending outcomes: current visibility gives a clearer picture of whether a business can support new borrowing.
This is a game-changer for businesses with volatile cash flows.
Flexible Repayment Structures
Ongoing access to data also allows lenders to design more flexible repayment structures.
Sector-Specific Benchmarking
With standardised data from thousands of SMEs, lenders can now build robust benchmarks for different sectors. A cleaning contractor's financial profile should look different from a software developer's. Open banking data allows lenders to see and react to these differences with precision.
From Rules-Based to Evidence-Based Assessment
This shifts assessment from ‘rules-based' to ‘evidence-based', a subtle but powerful change.
Faster Underwriting
Automation in Lending Decisions
When financial data is standardised and delivered via API, underwriting can be partly or fully automated, giving small and medium sized businesses and medium sized enterprises faster, more accurate decisions that support growth. Many lenders are now building scorecards that run in seconds, with human underwriters focusing only on edge cases or high-value deals.
The result: lending decisions in days instead of weeks. Some platforms can approve applications and release funds within 24 hours.
The Broker Advantage
Open banking benefits brokers enormously, but only if they're using finance broker software platforms designed to leverage it.
Efficiency Gains for Brokers
A broker armed with commercial finance broker software and open banking tools can now:
Broker capabilities:
- See verified financial data instantly, rather than asking clients to dig through files.
- Match clients to lenders in minutes, instead of researching 20+ possible options.
- Submit applications with complete, verified data, dramatically improving approval rates.
- Retain full independence and maintain 100% of commission.
Competitive Edge
The alternative is being left behind, working with the same manual processes, the same inefficiencies, the same time investment that made broking exhausting a decade ago.
Open banking doesn't just benefit lenders. It empowers brokers to compete more effectively and serve clients faster.
Challenges and Considerations
Open banking is transformative, but it's not without challenges.
Data Privacy and Security
With sensitive financial data flowing between systems, security is paramount. UK open banking operates under strict PSD2 and GDPR frameworks, requiring strong authentication and explicit customer consent so businesses can securely share data from a bank account with authorised third party providers. Access is permission-based and can be revoked at any time. This is correct, but it also means platforms must invest heavily in compliance infrastructure.
Brokers and lenders need to partner with SME lending deal origination platforms that take this seriously.
Data Quality Variation
Standardised data is only as good as the data being entered into the source system. A business using Xero but entering transactions haphazardly will still produce poor data. Open banking solves the delivery problem, not the quality problem.
Lenders still need to apply judgement and ask good questions.
Coverage Gaps
Not every business uses modern accounting software. Some small businesses and sole traders still rely on legacy systems or spreadsheets. open banking for sme lenders reaches most of the market, but not all of it, so lenders need fallback processes for these cases.
The best open banking solutions handle this gracefully, and the strongest open banking platforms offer manual upload options without degrading the overall user experience.
The Regulatory Tailwind
Policy Direction
Here's the interesting part: open banking isn't just a fintech trend. It's policy. The FCA has made open finance a central plank of its agenda, with an explicit roadmap to expand open banking into SME lending, insurance, and investment services through 2030, with clear relevance for medium sized enterprises smes and more cost effective lending models, and that open finance vision for SME lending is already being realised in practice.
Future-Proofing Operations
This means lenders investing in open banking infrastructure now are future-proofing their operations. The regulator is explicitly encouraging this direction. As regulation and infrastructure mature, this shift also supports tailored financial products and encourages lenders to evaluate modern loan origination software platforms that embed verified data and automation. New lenders entering the market are expected to use modern data standards from day one.
Lenders and brokers who adopt open banking early aren't just gaining competitive advantage. They're aligning themselves with the direction of regulation itself.
Looking Ahead: A New Standard for SME Lending
The Shift to API-Driven Lending
The shift from manual, paper-based lending to API-driven, open banking-based assessment is already underway. It's not a future vision; it's happening now, and accelerating.
In five years, lenders that still rely on manual data entry and historical accounts will be at a severe disadvantage. Brokers that can't access verified real-time data will struggle to compete. For uk's small businesses, open banking can also improve cash flow through faster payments, helping reduce late payments as funds settle sooner, especially as finance broker software begins to rival mortgage adviser technology in its sophistication. The question isn't whether to adopt open banking: it's when.
Opportunities for Alternative Lenders
For alternative lenders, this is an opportunity to level the playing field with traditional banks. Banks have scale, but they move slowly. Alternative lenders who embrace open banking and plug into a loan origination marketplace can move faster, make better decisions, and serve SMEs with real urgency. Beyond lending, businesses can give customers more ways to make payments through bank-to-bank options instead of traditional card payment methods or card schemes, and can also use bulk payments to automate supplier bills or employee salary runs. Alternatives to card payments, including qr codes and offering qr codes at checkout or on invoices, can lower transaction fees, which matters most for firms with lower transaction volumes and smaller profit margins.
Efficiency for Brokers
For brokers, it's a chance to unlock genuine efficiency and reclaim the time currently spent on admin, research, and verification by adopting commercial finance broker software. Many business owners can also save time and money, while better business decision making comes from real time insights. The brokers who thrive in the next decade will be those who use technology to enhance their expertise, not replace it.
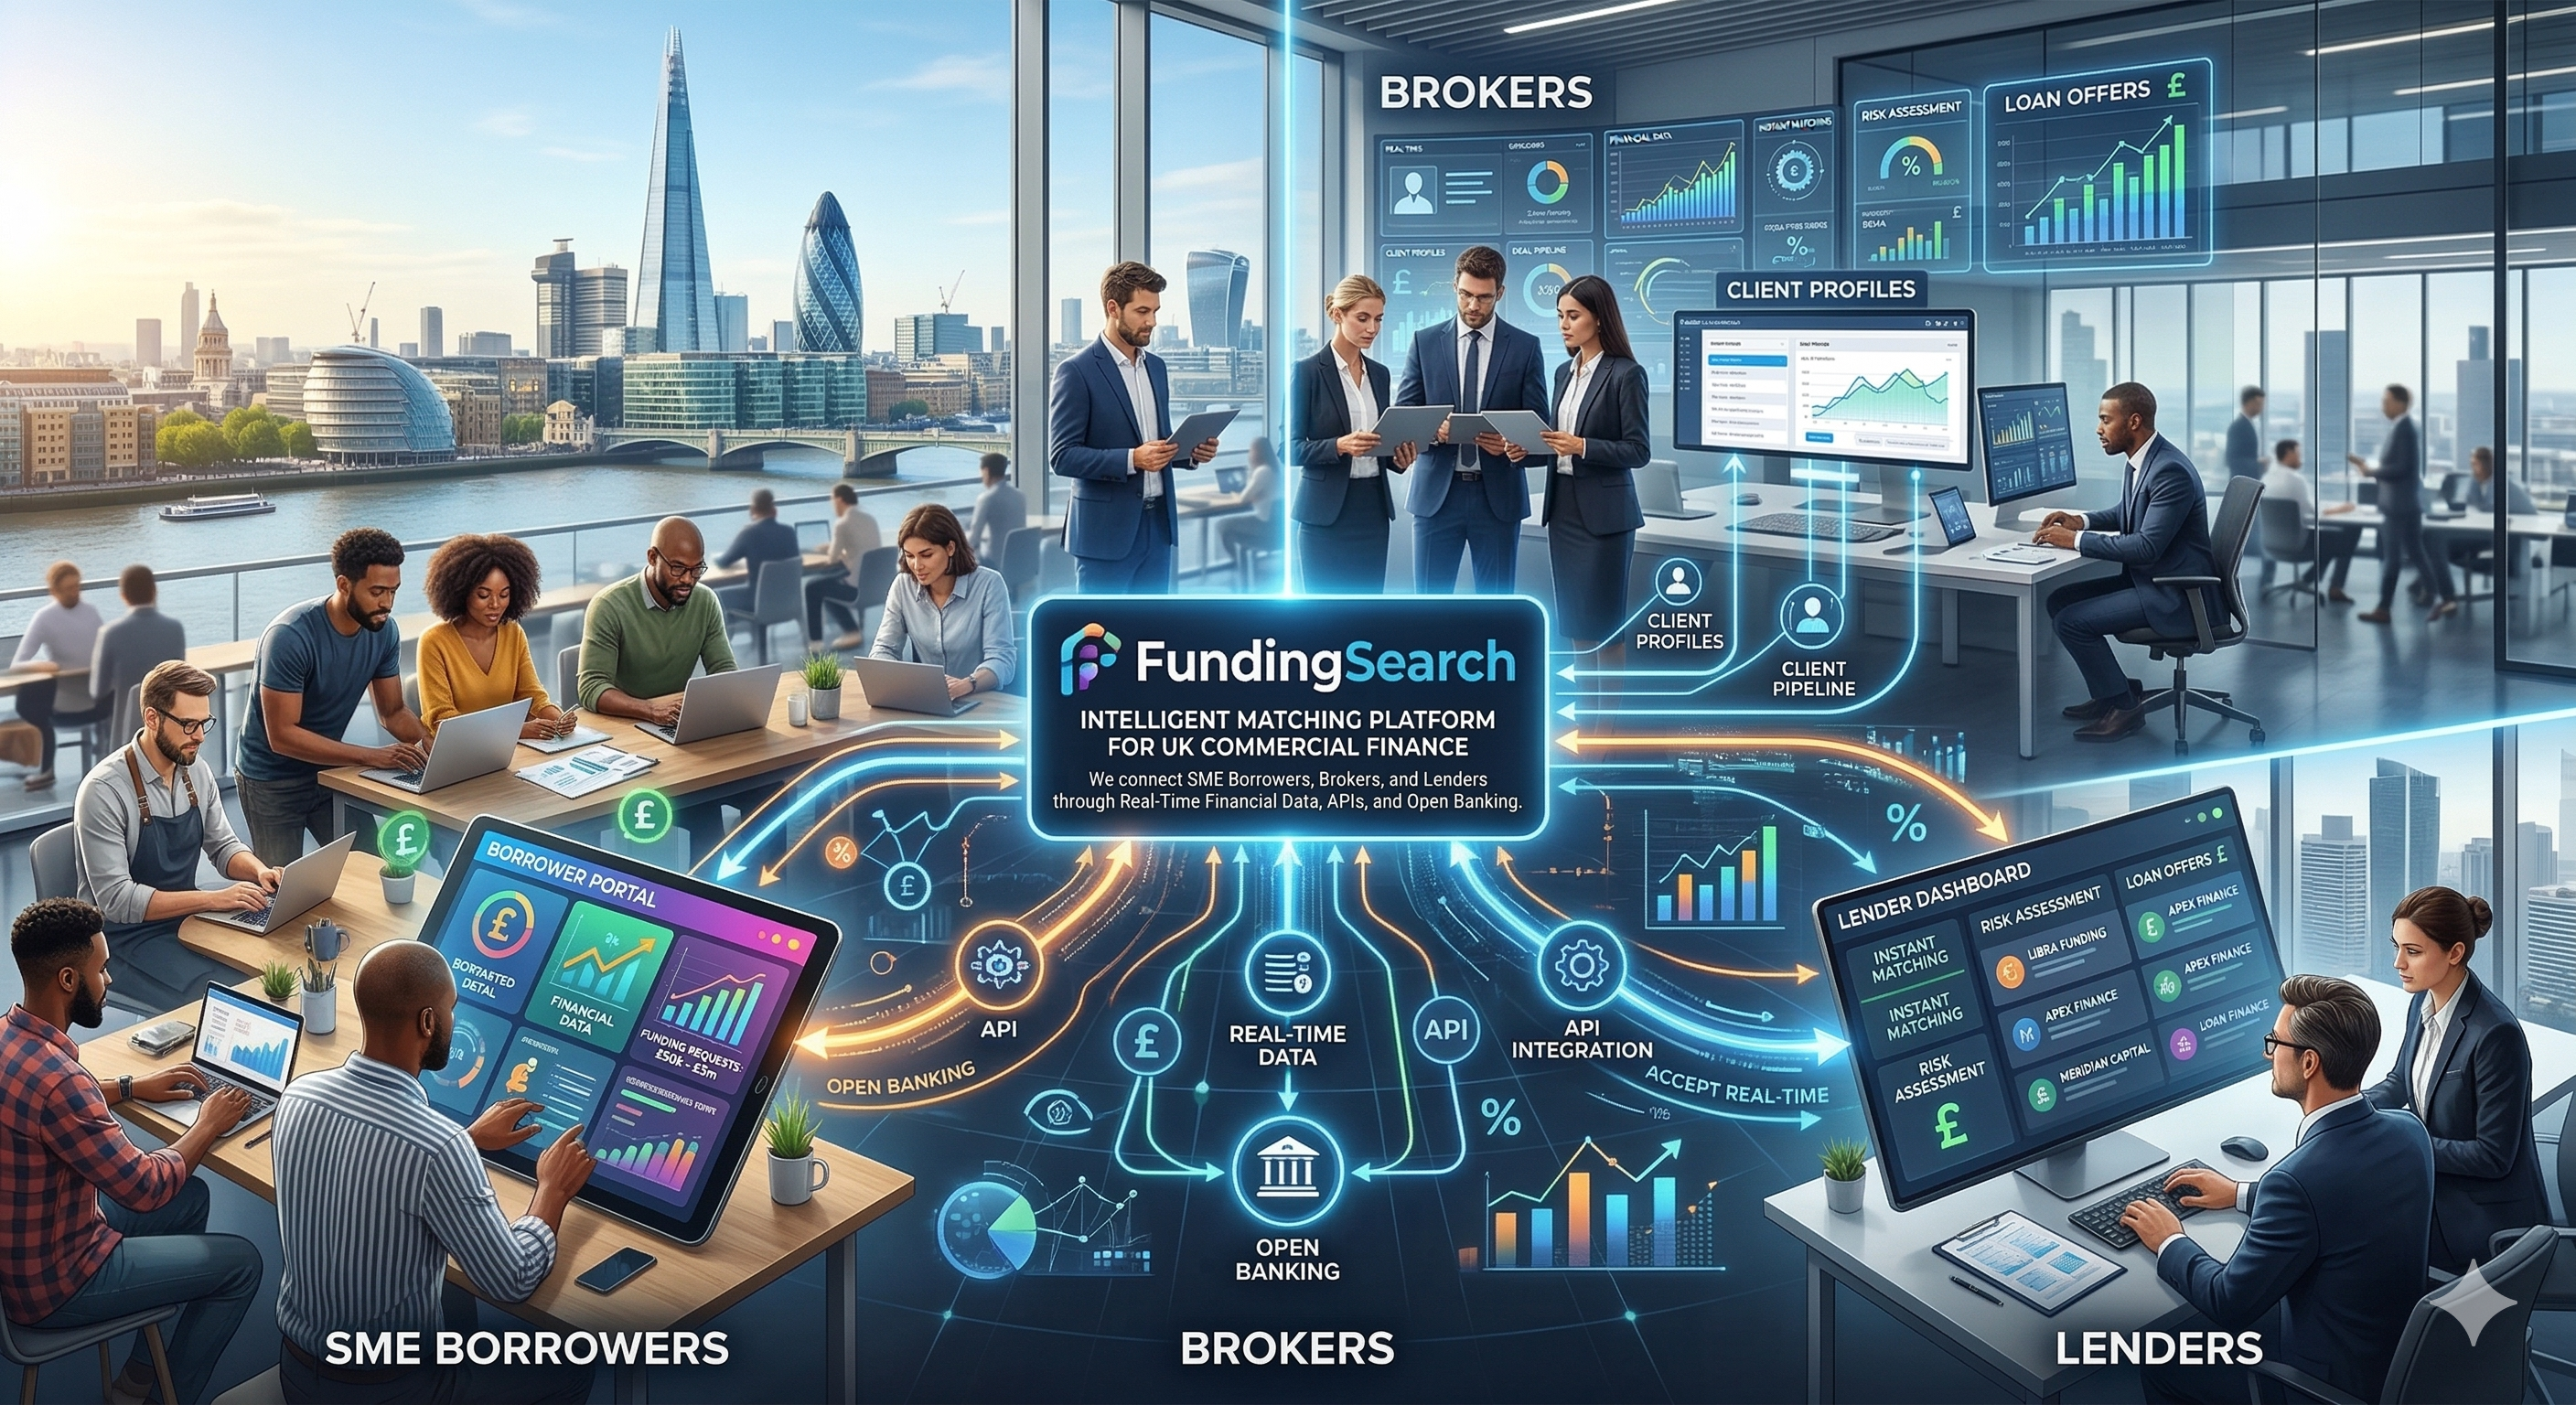
At FundingSearch, we've built open banking into our DNA. Our Xero and Sage integrations pull verified financial data directly into our lender matching engine, eliminating hours of broker research and dramatically improving application quality. We're not just riding the wave of open banking; we're helping to define what responsible, broker-first platforms should look like.
If you're a broker looking to embrace open banking, or a lender wanting to streamline creditworthiness assessment, the time to act is now.
Discover how FundingSearch's open banking platform can transform your lending operation. Visit fundingsearch.com or contact Phillip Evans