All Posts
4 min read
Debt Factoring: How It Works, When It's Suitable, and Smarter Ways to Improve Cash Flow
Published on 15 September 2026
If your business invoices other businesses on credit terms, you already know the frustration of waiting 30, 60, or even 120 days for customer payments to arrive. Debt factoring offers one practical way to close that gap.
Introduction to Debt Factoring
Debt factoring means a business sells its unpaid invoices to a third party factoring company as a financial arrangement and short-term financial solution to unlock tied up capital, in exchange for an immediate cash advance, typically receiving the majority of the invoice amount within 24 to 72 hours. The factoring company takes over credit control, chasing payments and collecting payment from customers on the business's behalf.
UK SMEs in sectors like recruitment, manufacturing, logistics and construction regularly turn to debt factoring when cash is tied up in long payment terms. A recruitment agency placing contractors weekly but waiting 45–60 days for invoice payment, or a manufacturer supplying large retailers on 90-day terms, can use factoring to access working capital and maintain healthy cash flow before its reserves are squeezed to breaking point despite strong sales.
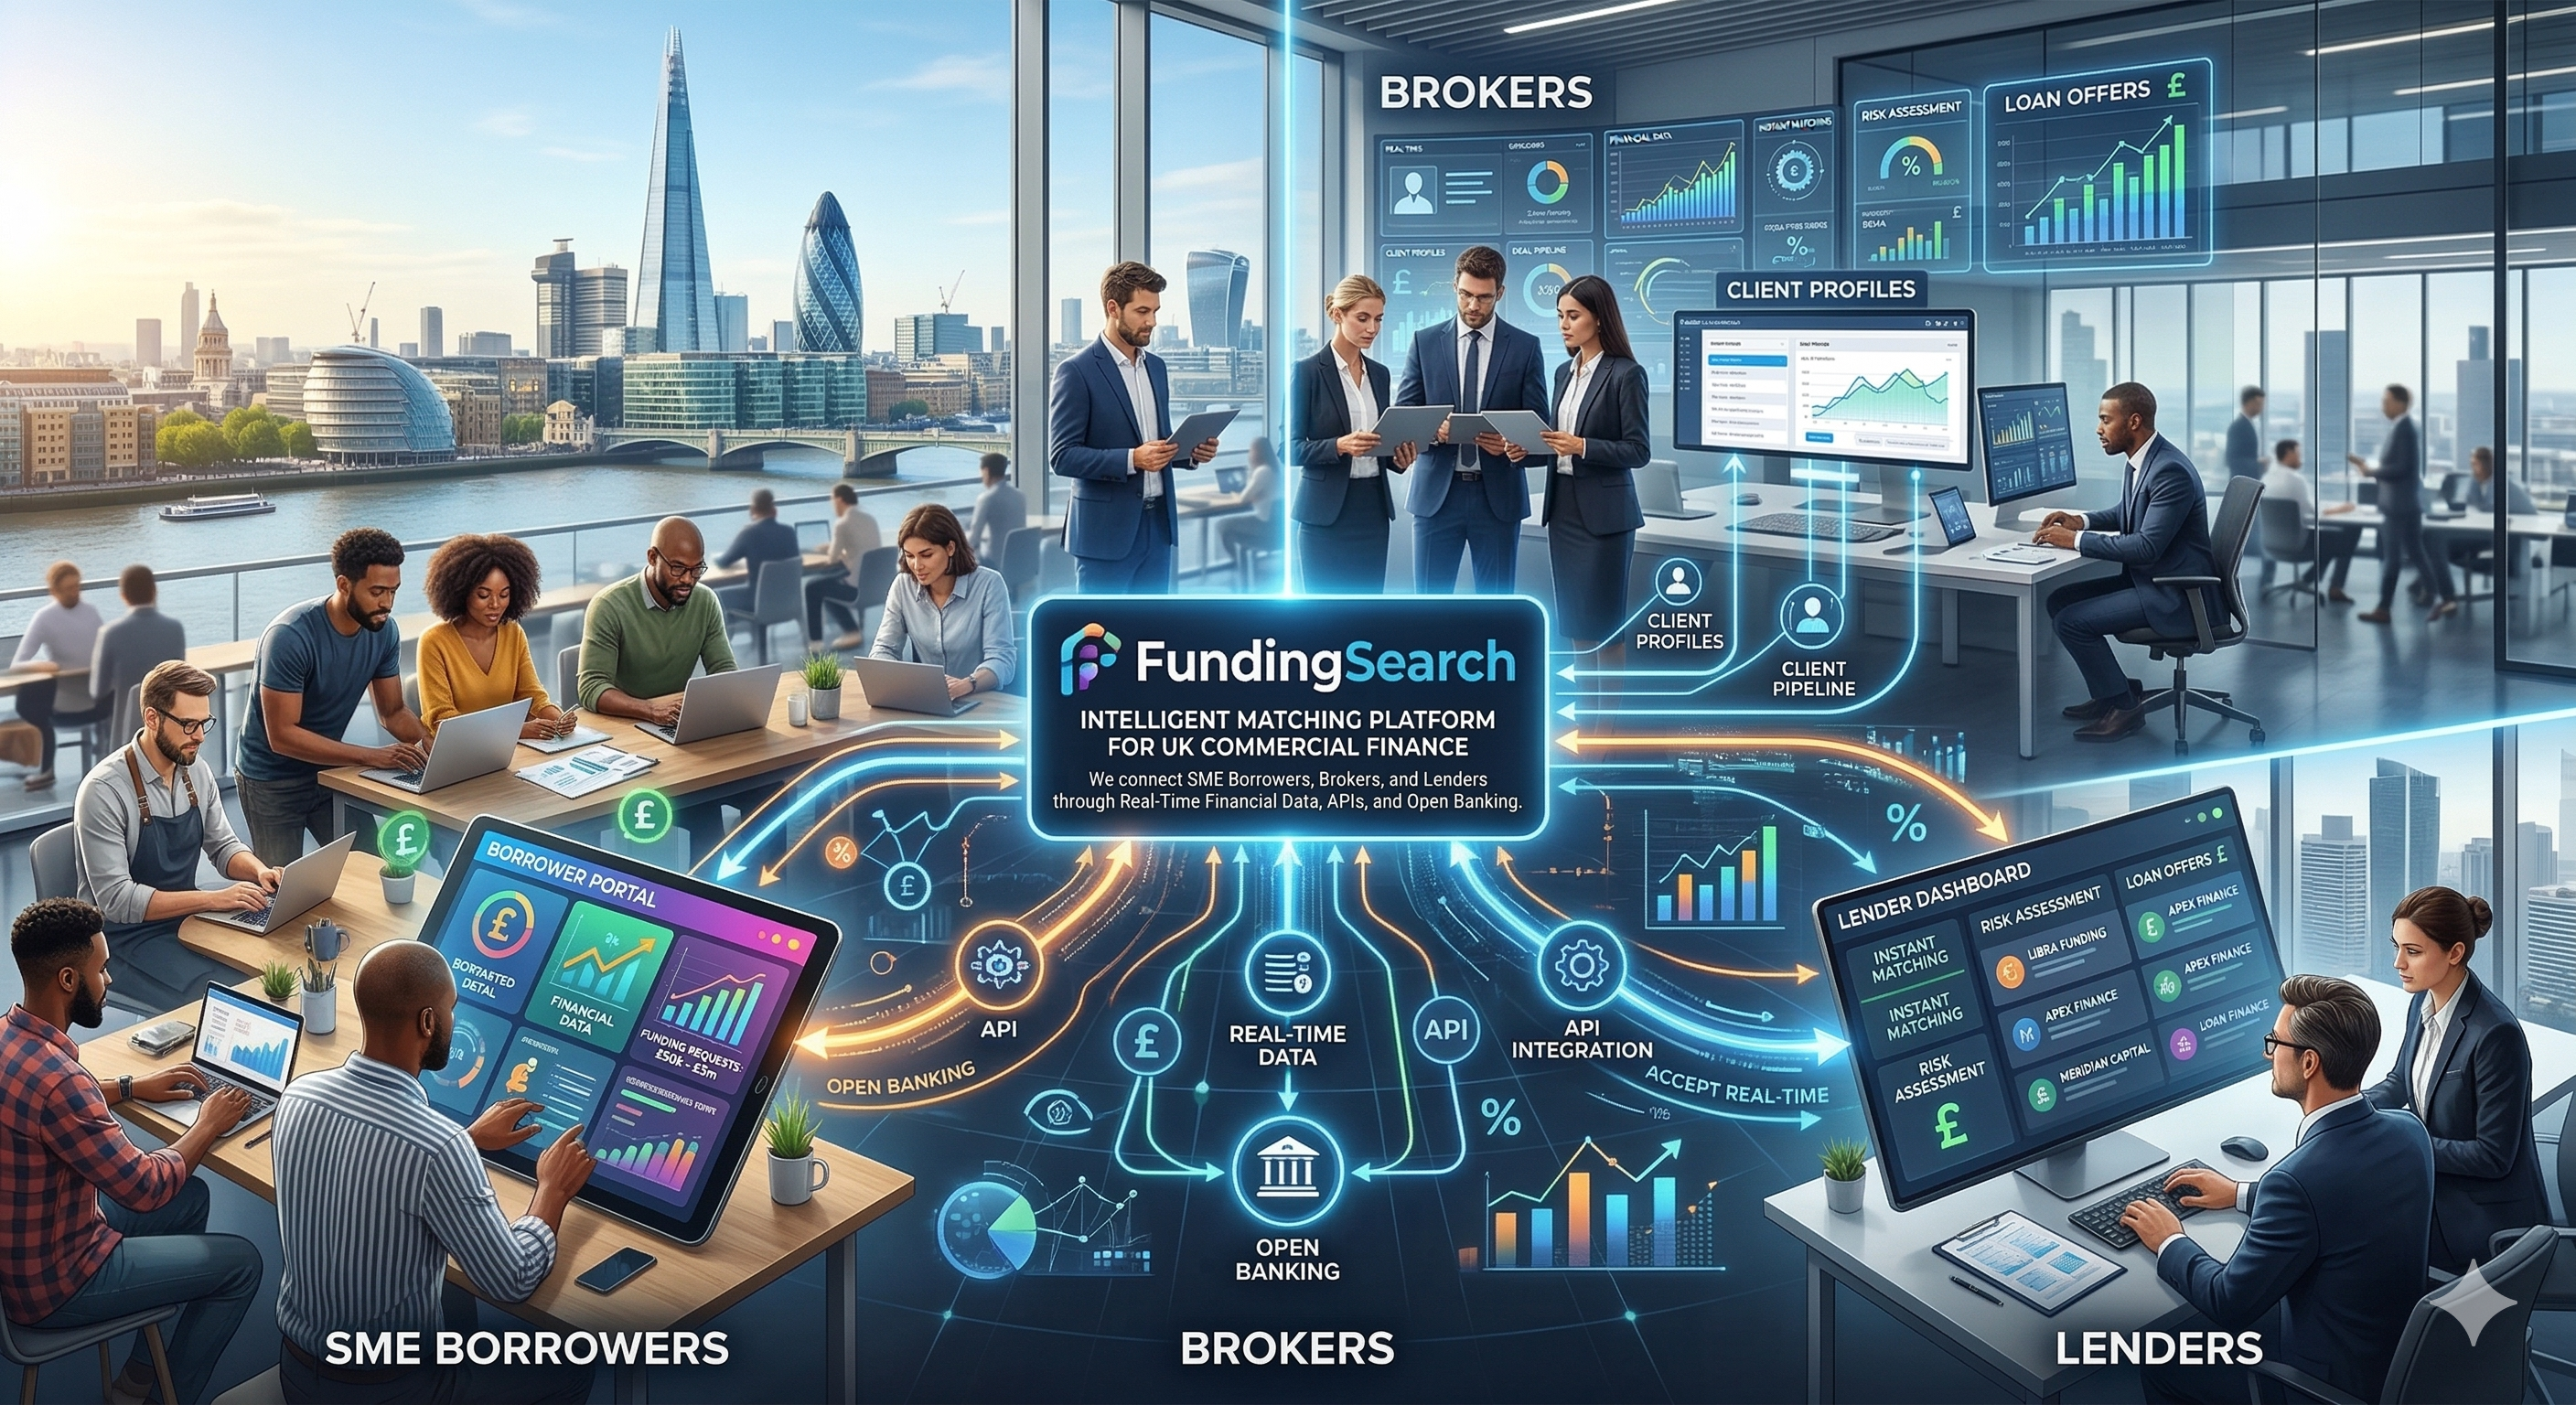
Debt factoring is one form of invoice finance, sitting alongside invoice discounting, selective invoice finance and other receivables solutions. Each variant handles collections, customer visibility and risk differently. FundingSearch helps small business owners compare and use factoring by matching verified financial data with suitable providers across a panel of lenders.
What Is Debt Factoring and How Does It Work?
Debt factoring explained: the process typically involves four simple steps in practice.
A business delivers goods or services to a customer and issues an invoice on agreed payment terms, say 60 days. To show how debt factoring work, the business sells unpaid B2B invoices to a factoring company rather than waiting for payment. The factor verifies the invoice, then advances a percentage of the invoice value, usually 80–90%, directly to the business. Some providers can advance up to 100% of invoices under specific arrangements, though 85% is more common.
The factoring company then manages the sales ledger for those invoices. In simple terms, how invoice factoring work is that the provider releases funds against approved invoices, handles administration tasks like credit control and invoice tracking, and then contacts the customer, sends reminders and collects payment. Businesses can access funds within 24 to 72 hours of submitting an invoice, rather than waiting weeks or months.
When customers pay the invoice in full, the factor deducts its fees (a service fee and a discount fee) and remits the remaining balance to the business. Unlike a term loan, this is an ongoing facility tied to your sales ledger, not a one-off lump sum of additional debt. As you invoice more, more funding becomes available.
If the customer delays payment, the discount charge continues to accrue, which is why factoring costs can vary significantly depending on how quickly customers pay, and that structure is what makes debt factoring attractive when businesses need faster cash than traditional borrowing.
Worked Example of Debt Factoring in a UK SME
Imagine a UK limited company with monthly B2B sales of £60,000, all on 60-day terms. On 1 March it issues a £20,000 invoice due 30 April. It enters a factoring arrangement with these terms: 85% advance rate, 1.5% service fee on the invoice amount, and a discount rate of 6.75% per annum (BoE base rate at 3.75% plus a 3% margin).
The key figures break down as follows. The cash advance is £17,000 (85% of £20,000), paid within hours. The reserve held back is £3,000. The service fee is £300 (1.5% of £20,000), plus £60 VAT. The discount charge on the advance for 60 days is approximately £178 (£17,000 × 6.75% × 60÷365).
When the customer pays in full on 30 April, the factor returns the reserve minus fees: roughly £3,000 − £300 − £60 − £178 = £2,462. Combined with the initial £17,000, the business receives approximately £19,462, making the total cost around £538 or 2.69% of the invoice value.
If the customer instead makes late payments and pays 30 days late (90 days total), the discount charge rises to approximately £266, pushing the total cost to over 3.1%. This illustrates how delayed payments directly inflate the associated costs. Factoring fees typically range from 1% to 5% of invoice value depending on terms, sector and debtor quality, and factoring can shorten the cash-conversion cycle substantially for businesses operating with long payment terms.
Debt Factoring Advantages and Disadvantages Overview
Every business should weigh the advantages and disadvantages of debt factoring before signing an agreement. The benefits can be powerful, but the costs and risks can erode margins if not properly understood.
The main debt factoring advantages at a high level include improved cash flow through immediate access to funds to help maintain steady cash flow, reduced admin burden by outsourcing the collection process, the ability to access funds without taking on traditional loans, and a facility that scales naturally as sales grow. Debt factoring is also easier to qualify for and faster to access than bank loans, since the factor's decision is based primarily on your customers' creditworthiness rather than your own balance sheet.
The key disadvantages of debt factoring include fees that erode margin over time, the potential impact on customer relationships when a third party factoring company handles collections, and poor handling can damage customer relations as well as trust, contractual commitments that can restrict flexibility, and the risk of dependency on factoring for day-to-day liquidity. Debt factoring can reduce overall profit margins significantly if used on every invoice without careful cost management, and it can be more expensive than traditional loans.
The sections below go deeper into both sides, including bad debts, recourse vs non-recourse factoring, and how factoring compares to invoice discounting.
Advantages of Debt Factoring: When It Can Improve Cash Flow
The core advantage is timing. Debt factoring improves cash flow by providing immediate cash advances against outstanding invoices, converting accounts receivable into immediate working capital. Instead of waiting 60 or 90 days for customers to pay, businesses can access funds quickly and use that cash to maintain steady cash flow for payroll, suppliers, stock, and growth.
Outsourcing credit control and debt collection to the factor saves internal administrative time. Many factors also perform credit checks on your customers and monitor your aged debt, which can reduce exposure to overdue payments, bad debts, and the financial stress caused by slow-paying customers, particularly if non-recourse elements are included. It allows businesses to grow by unlocking capital tied in invoices without adding additional funding obligations or extra financial strain.
Factoring does not usually appear as long-term balance-sheet debt in the same way as a bank loan, which can help maintain financial stability ratios that directors and other lenders monitor. More predictable cash flow can also improve a business’s financial position with suppliers and strengthen bargaining power. For a business that needs to onboard a new contract, import stock ahead of peak season, or hire staff without waiting months for invoices to clear, this kind of access can be transformative. A small business owner may prefer emergency business loans for urgent financial needs to cover operating costs and support growth while waiting for invoice payment, especially when the business lacks the trading history required for conventional lending.
Disadvantages of Debt Factoring and Common Pitfalls
Cost is the most significant drawback. Between the service fee (typically 0.5–3% of turnover) and the discount charge (often BoE base rate plus 2–4% margin), the total factoring fee on a single invoice can be material. Frequent use of factoring can lead to escalating costs, particularly if customers are slow payers or facing long payment cycles, because the discount charge accrues daily on drawn funds.
Using a factoring company may negatively impact customer relationships. Customers receive assignment notices and deal with a third party for collections. If the factor's approach is assertive or impersonal, it can affect repeat business and brand perception. Disputes handled through the factor can also strain customer relations, as some customers may see the arrangement as a sign of financial strain. Some businesses operating in relationship-sensitive sectors find this a serious concern.
Contractual pitfalls are common. Many factoring companies place requirements around whole-turnover commitment, meaning you cannot selectively factor only certain invoices. Fixed-term contracts, long term contracts, notice periods of three to six months, and minimum monthly fees can lock businesses into arrangements that no longer suit them. Factors usually reject invoices from financially weak customers or disputed accounts, narrowing the eligible portion of your ledger.
In recourse factoring, the business remains liable in cases of non payment if the customer does not pay. This means bad debt still sits on your risk profile despite having received an advance. Debt factoring introduces short-term debt for businesses in this way. Before signing, compare offers and seek professional advice. FundingSearch's broker platform helps match businesses with suitable invoice finance providers while surfacing hidden costs and contract terms.
Is Debt Factoring Suitable for Your Business?
Debt factoring is most suitable for UK B2B businesses invoicing on credit terms of 30 to 120 days, though some firms may also compare it with accounts receivable financing. It is typically used by businesses with annual turnover above £50,000 and a reasonably diversified customer base, and those with clients whose credit scores or overall credit worthiness support approval tend to benefit most because the factor assesses debtor strength when setting advance rates and pricing. For firms where cash flow pressure is mainly caused by payment timing rather than weak demand, it can be a practical financial solution.
Concrete sector examples include recruitment agencies paying contractors weekly but waiting 45–60 days for invoice payment, transport and haulage firms with fixed payment cycles, wholesalers supplying large retailers, and construction subcontractors managing stage payments. Debt factoring is ideal for B2B businesses with delayed payments in these sectors.
Debt factoring is generally limited to B2B invoice sales and usually does not apply to consumer transactions or businesses with very low invoice turnover. Businesses with heavy concentration in a single high-risk customer, or those whose margins are too tight to absorb the fees, should think carefully. If your cash flow issues stem from unprofitability rather than timing, factoring will not solve the underlying problem.
A practical checklist to consider: is your annual turnover sufficient (above £50,000)? Are your customers creditworthy and diversified? Are your payment terms long enough that cash flow challenges are driven by timing? Are you comfortable with a third party collecting payment from your customers? Can you absorb 1–5% in fees without damaging your margin? If these answers are mostly yes, a debt factoring facility is likely worth exploring with your broker or accountant.
Debt Factoring vs Invoice Discounting and Other Alternatives
The most common comparison is between debt factoring and invoice discounting. In factoring, the factoring company takes over managing invoices and chasing payments, and customers are typically aware of the arrangement through a debt assignment notice. In invoice discounting, the business retains control of its sales ledger and collections. The key difference in payment collections is that factoring shifts them to the provider, while financing leaves them with the business. In confidential arrangements, customers may not know that invoice finance is in place at all. Invoice discounting allows businesses to retain control of collections and tends to suit more established businesses with robust internal credit control.
Beyond these two, alternatives include business loans, overdrafts, asset-based lending, trade finance solutions, receivable financing, and newer B2B solutions that also target late-payment and unpaid bills problems. Low interest business loans or asset finance may be cheaper in headline terms but slower to access and often require collateral or guarantors.
Both factoring and discounting help avoid taking on large one-off additional debt facilities, but costs and flexibility vary significantly between providers. The right choice depends on whether you need the factor's credit control support or prefer to retain control, whether you want to offer trade credit to customers without straining your own cash, and how your business goals align with each product's structure, including whether you want to collect payment yourself or use an option that lets you retain ownership of invoices rather than sell the receivables.
FundingSearch lets SMEs, brokers and advisers compare invoice finance alongside other commercial finance products on one platform, using verified financial data to match with suitable lenders quickly.
Managing Risk: Recourse, Non-Recourse and Bad Debts
Understanding risk allocation is critical before entering any factoring arrangement. Non-recourse factoring allows the factor to assume the credit risk of the customer, meaning the factor absorbs certain bad debts and may offer bad debt protection if the customer cannot pay, subject to agreed limits and conditions. Recourse factoring means the business remains liable if the customer does not pay, effectively pushing the unpaid invoice back to the business.
Non-recourse features help manage the impact of bad debts but usually come at a higher cost and with strict criteria about which customers and invoices are covered, with the factoring agreement setting the limits and conditions for that cover. Financial institutions offering non-recourse typically require strong debtor credit profiles and undisputed invoices.
Practical ways to reduce risk within any facility include performing robust credit checks before extending trade credit, setting realistic credit limits per customer, monitoring aged debt closely, and resolving invoice disputes promptly to avoid losing eligibility. Some factors integrate with accounting platforms like Xero and Sage to monitor ledgers in real time, and FundingSearch is designed to connect those data sources to lenders for smoother underwriting and better pricing.
How to Compare Factoring Companies and Use FundingSearch
When comparing a debt factoring company against competitors, focus on these key points: the advance rate offered (80–90% is standard), the full fee structure including service fee and discount margin, contract length and notice period, minimum monthly fees, sector expertise, the provider's approval process, how quickly it can verify invoices and release funds, and the quality of the credit control service provided.
Do not focus solely on the headline percentage. Consider how the provider will treat your customer relationships, how quickly decisions and drawdowns are made, and whether the contract allows you to receive payment flexibly as your medium sized enterprises' needs evolve.
An invoice factoring company that specialises in your sector often understands payment practices, offers better advance rates, and provides more realistic pricing for your specific debtor profile.
FundingSearch, as a UK business commercial finance marketplace, lets SMEs and commercial finance brokers compare a wide panel of invoice finance and factoring providers in minutes. Instead of approaching each lender separately, the platform uses verified financial data from Companies House, Xero and Sage, combined with AI-driven matching, to pre-qualify deals and present lenders more likely to approve based on the debtor book rather than only the business's own profile. This reduces wasted time and failed applications for both brokers and borrowers.
The UK invoice finance market advanced over £22 billion to businesses in Q2 2026 alone, yet only around 3% of SMEs currently use these facilities. For many, the barrier is not eligibility but simply not knowing which product or provider fits best. Whether debt factoring, invoice discounting, or another product is the right answer for your cash flow needs, start a free search on FundingSearch to find out.