Business Lending Software: Connecting SMEs, Brokers, and Lenders
FundingSearch is a UK-based SME lending deal origination platform and digital distribution layer, enabling brokers to submit structured funding opportunities and allowing lenders to source qualified deal flow aligned to their credit appetite.
As featured in
A Software Platform for Every Business Funding Role
FundingSearch is a UK-based SME loan sourcing & deal origination platform that enables lenders to access structured deal flow through a digital distribution network of brokers and borrowers. Designed for modern commercial finance, the platform replaces fragmented sourcing with scalable, technology-driven origination.
Commercial Lenders
Brokers & Advisors
Borrowers
What is a Deal Origination Platform?
A deal origination platform is a digital system that connects lenders with funding opportunities from brokers and borrowers. It improves deal flow quality, speeds up matching, and enables scalable lending distribution.
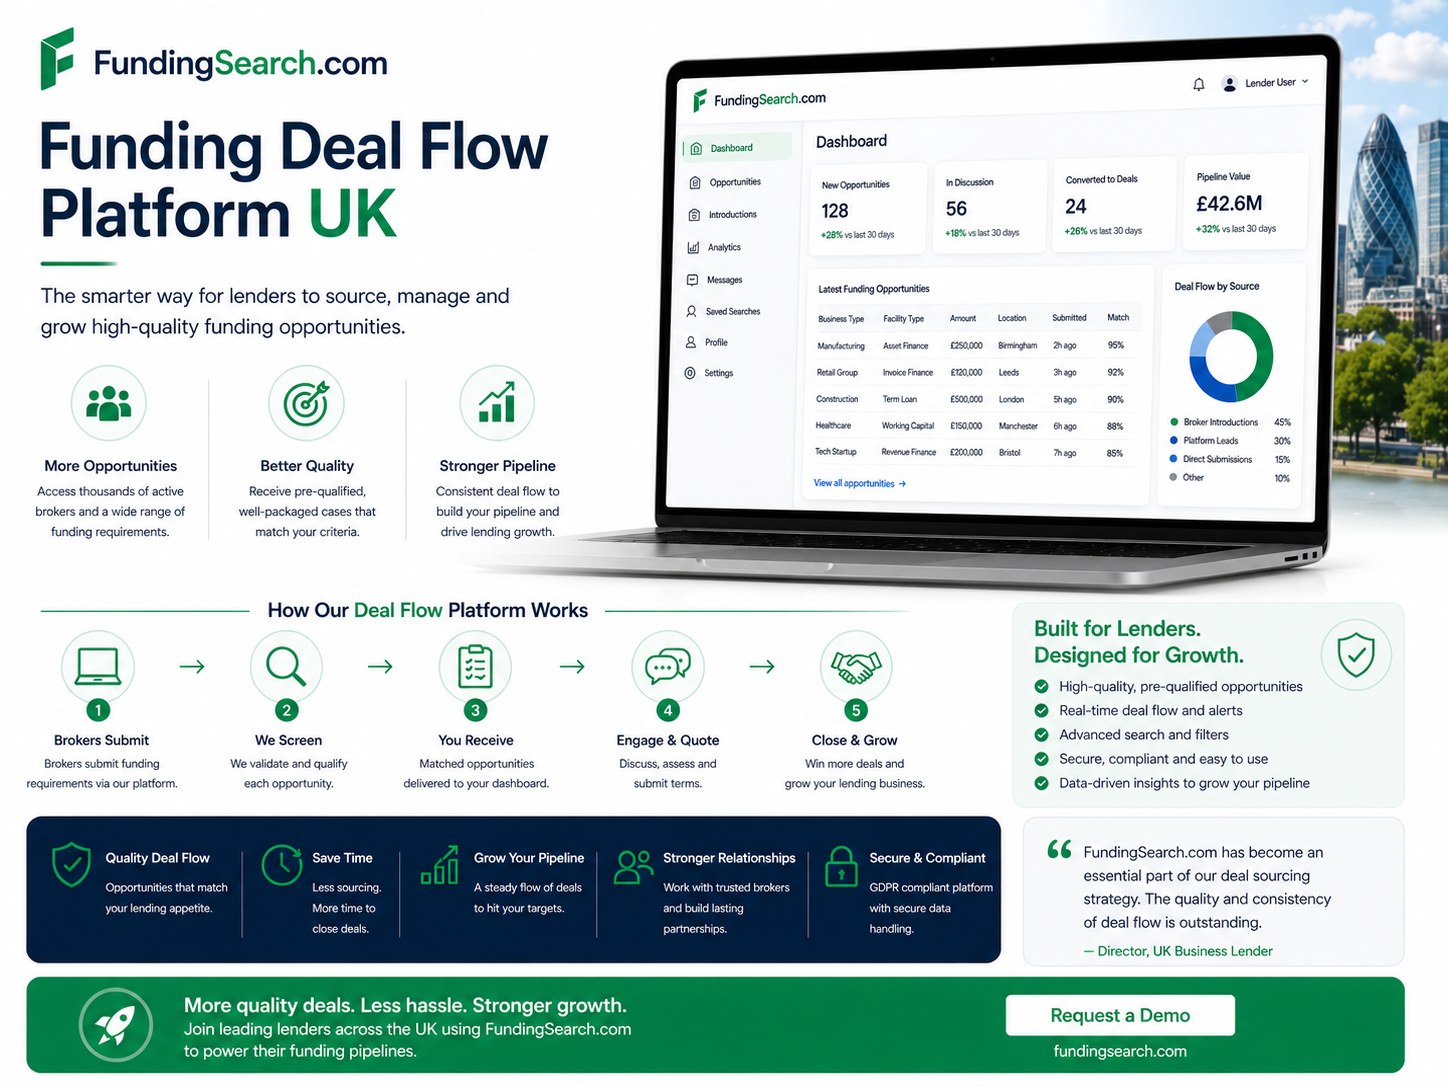
Deal Origination Platform
Start by clicking 'Get Started' and following our guided onboarding process

Commercial Finance Sourcing Software
Source, match and place commercial finance deals faster through a unified broker–lender platform.
Lender Deal Flow
Access consistent, high-quality deal flow from active brokers through a structured digital distribution platform.
Trusted & Compliant
Fully GDPR compliant processes designed to protect both borrowers and lenders.
GDPR Compliant
Secure Data Processing
Trusted by UK Brokers & Lenders
Data Driven Fintech Solutions For Brokers, Lenders & Borrowers
An intelligent business loan matching platform for commercial finance brokers, trusted advisors and lenders. Borrowers, the outcome for you is the speed of fintech and AI intelligence, with the reassurance of a professional ready to take your funding application through to completion.
Matching Across Distinct Data Points
Deliver higher-quality deal flow through verified financial data and intelligent origination matching

Time Saved Filling Out Forms
Companies House integration, data pulled from the accounts software, reduces the time you spend filling out forms
Typical Client Onboarding Timeline
Brokers can onboard clients in less than 10 minutes

We’ve got what you need
Designed for entrepreneurs who demand more from their lending partner
Digital Application
Complete your entire loan application online in minutes with Companies House integration.
AI-driven match
Our technology finds the most suitable lenders for your specific business needs.
Your Broker On Hand
The reassurance of a professional commercial finance broker managing your application through to completion

See how much time you save?
Funding Search is all about smart data, AI processes and fintech deployment, so your time is back in your hands.

Conquer the chaos, try Funding Search Today
Whether you're a busy finance professional with complex cases to place, a commercial lender looking to take advantage of Open Finance or improve efficiencies or a busy entrepreneur looking to fund your growth, FundingSearch has you covered.
Published on 22 September 2026
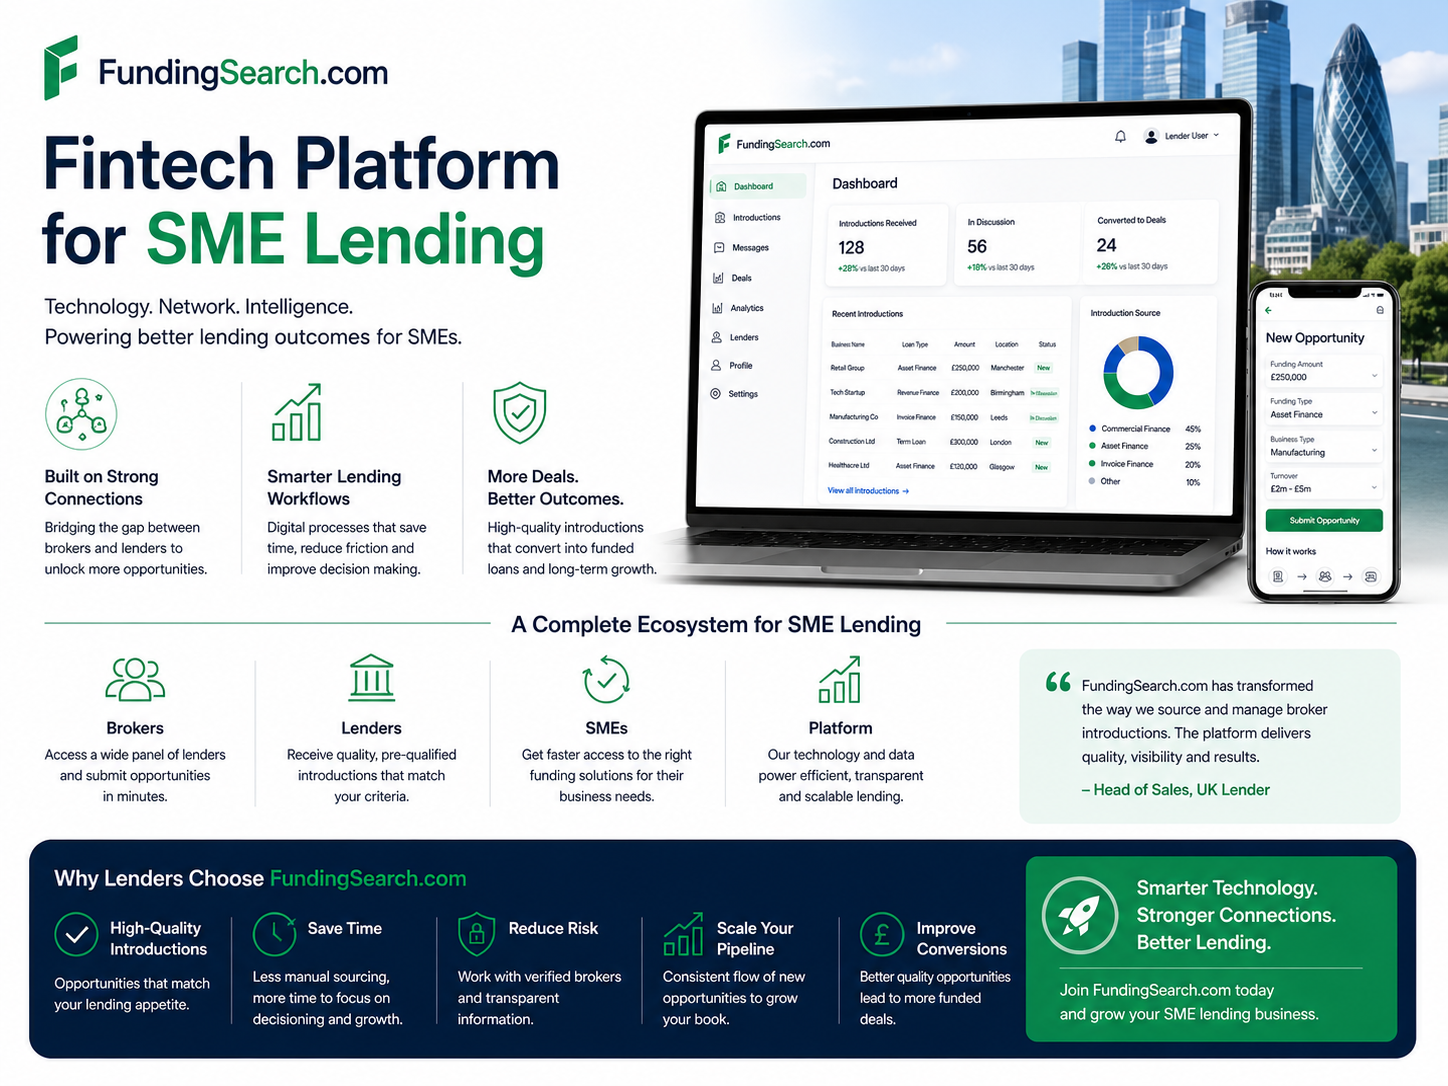
Business lending software built for UK SMEs, brokers and lenders
Business lending software is transforming how small and medium sized enterprises (SMEs), brokers, and lenders connect and transact in the UK. In 2026, business lending software does far more than digitise a paper form—it is the technology layer that connects SMEs seeking capital with the brokers who advise them and the lenders who fund them, automating processes from first enquiry through to credit decision and drawdown.
This page covers the full scope of business lending software: what it is, how it works, the key features to look for, and how it benefits each party; SMEs, brokers, and lenders. The target audience includes UK SMEs, commercial finance brokers, and alternative or specialist lenders. The topic is especially important now due to a changing lending landscape, tighter credit policies, and the growing need for efficiency and speed in business finance.
For UK businesses navigating tighter credit policies, elevated interest rates and an increasingly complex lending market, the right platform can mean the difference between waiting weeks for an answer and receiving realistic funding options in days.
FundingSearch is a deal origination platform, not a public marketplace. Built in Sheffield and launched in 2025, it connects borrowers with vetted commercial finance brokers and regulated lenders through a closed, curated network. Every participant is verified, every dataset is structured, and every match is driven by artificial intelligence trained on real lender criteria and historical approval patterns. The result is a business lending platform purpose-built for the way commercial finance actually works in the UK.
The platform supports business loan origination and ongoing deal management across seven distinct asset classes: business loans, commercial mortgages, bridging finance, invoice finance, asset finance, asset-based lending and trade finance. Whether an SME needs £50,000 of working capital or a broker is structuring a blended facility combining term loans with invoice finance, FundingSearch handles the complexity inside one commercial finance lending platform.
This page explains how modern business lending software works, why it matters now, and how FundingSearch specifically helps each party in the lending process achieve better outcomes. Here is a quick summary of who it serves and what it solves:
- SMEs and limited company directors – gain access to multiple lenders without repeating applications, uploading the same documents or facing unnecessary hard credit checks. Faster decisions, clearer options, no upfront costs.
- Commercial finance brokers and advisers – manage pipeline, match deals to lenders using AI, reuse company data across applications and collaborate with lender BDMs without email chains using dedicated commercial finance broker software. Enhancing productivity and doubling case volume becomes realistic.
- Alternative and specialist lenders – receive only pre-qualified, policy-fit deal packs with verified financial data, reducing operational risk and wasted underwriting time. Higher conversion, lower cost per approved case.
Why traditional business lending is broken for SMEs in 2026
The post-Covid UK lending landscape has not returned to easy money. Interest rates remain higher than the decade preceding the pandemic, and many banks - including community banks and large financial institutions alike - have tightened credit policy, demanding more security, longer trading histories and thicker documentation from borrowers. The British Business Bank's 2025 report notes that fewer smaller businesses are applying for external finance, even as the nominal value of SME bank lending stock has climbed to roughly £198 billion.
The typical journey for an SME seeking a business loan in the UK still looks remarkably manual. A business owner compiles two or three years of management accounts, exports bank statements as PDFs, fills in an application form, emails the pack to a broker, and waits. The broker then rekeys key figures into one lender's portal, reformats documents for another, and chases missing information by phone. If the first lender declines, the whole cycle restarts with the next. For a £250,000 working capital request, three to four weeks from first enquiry to credit decision is still common at many banks.
Each party absorbs unnecessary pain:
- Borrowers face slow responses, confusing criteria that vary from lender to lender, and the frustration of repeating the same financial information for every application. Many never discover the full range of funding options available to them.
- Brokers spend hours on document management, rekeying details into separate lender portals and guessing which lender will actually fund a case. Human error creeps in with every manual transfer of data.
- Lenders receive poor quality inbound deals - incomplete data, wrong sector, outside policy - and spend expensive underwriter time on cases that were never a fit. Operational efficiency suffers, and good deals get buried under noise.
Automated workflows eliminate bottlenecks in loan origination. Small business lending software automates loan applications and approvals, and effective business lending software reduces approval times from weeks to hours. This is the gap that AI-driven origination platforms like FundingSearch are designed to close.
What is business lending software?
Business lending software automates loan applications and approvals, improves operational efficiency across the loan lifecycle, and tracks the entire lifecycle of a loan.
Business lending software is a broad category of platforms and tools that digitise and automate the lifecycle of a business loan - from origination and pre-qualification through to offer, drawdown and, in some cases, ongoing servicing. Digital application processes increase efficiency for both borrowers and lenders, and investing in robust business lending software is critical for managing risk and streamlining operations.
Not all lending software does the same job. The market divides into three distinct categories, and understanding the differences matters when choosing a solution:
- Loan origination platforms (like FundingSearch) focus on sourcing, matching and packaging deals. They aggregate borrower data, apply lender rules and AI scoring, and route structured application packs to the right lenders. Their value sits at the front of the lending process - before a facility is approved.
- Loan management and servicing systems take over once the loan is live. A unified loan management system tracks the entire lifecycle of a loan, handling repayments, covenants, draw schedules and portfolio monitoring, including tracking repayment performance and early warning indicators for risk management.
- Comparison websites and marketplaces list lenders and products publicly but rarely integrate applicant data, verified financials or structured underwriting. They generate leads, not qualified deal packs.
FundingSearch sits firmly in the origination space. It connects SMEs, brokers and lenders using AI matching, verified open finance data and smart workflows - going well beyond what a simple comparison site can offer, and operating as advanced commercial lending software for UK institutions.
Key processes that business lending software typically covers include: application intake, KYC/KYB verification (built-in compliance tools enforce KYC and AML regulations), data aggregation from Companies House, accounting systems and open banking, initial scoring and credit assessment, policy matching against lender criteria, audit ready documentation, and handoff to lender systems for final decisioning and drawdown.
Why FundingSearch works for modern business lending
The benefits of lending technology are clear in theory. What matters is whether a specific platform delivers them in practice, for the people who actually use it. FundingSearch was built from the ground up around the workflows of UK commercial finance brokers, alternative lenders and SME borrowers - not retrofitted from consumer lending or imported from another market.
Launched in 2025 as a UK-based platform, FundingSearch operates as a closed network. Only verified brokers and lenders can access deals. This is a deliberate design choice: a curated network improves data quality, builds customer loyalty and ensures that every participant has been vetted for competence and regulatory compliance. It is a platform, not a marketplace - and certainly not a broker itself.
The core outcomes FundingSearch delivers are measurable: better-matched deals that fit lender appetite, faster business loan origination through automation and data integration, reduced rekeying across multiple applications, and higher conversion rates for brokers and lenders alike. Automated loan processing improves operational efficiency across the loan lifecycle, and these platforms support scalable operations for varying loan volumes.
Core benefits of using FundingSearch as your business lending software
- SMEs: Access multiple lenders with a single application, avoid repeated document uploads, and receive faster, clearer funding decisions with no upfront costs.
- Brokers: Manage all cases in one platform, match deals to lenders using AI, reuse company data, and collaborate with lender BDMs without email chains—doubling productivity and case volume.
- Lenders: Receive only pre-qualified, policy-fit deal packs with verified financial data, reducing operational risk, wasted underwriting time, and cost per approved case.
- AI-driven matching: AI engine matches SMEs to suitable brokers and lenders, ranks options by approval likelihood, and speeds up loan approvals to under 24 hours for many cases.
- Verified open finance data: Integrates with Companies House, Xero, Sage, and open banking for live financial data, reducing paperwork and manual uploads.
- Faster origination: Pre-qualification and smart routing compress the lending process from weeks to days or hours for simpler products.
- Better risk insight: Structured datasets and real-time analytics help underwriters make confident decisions, even on complex cases.
- Streamlined workflows: Brokers can track statuses, reuse data, and enhance client relationships through automated communication and reduced manual errors.
- No added cost for borrowers: SMEs access FundingSearch matching for free, with monetisation focused on broker and lender subscriptions.
How FundingSearch business lending software works
The process is intentionally straightforward for each party - borrower, broker and lender - while the complexity happens behind the scenes. B2B lending software automates loan servicing processes, and automated workflows can accelerate loan origination and closing.
Step 1: Connect business data and funding needs
A borrower or broker creates a case by entering company details (UK limited company registration number, sector, directors), the funding requirement (for example, £150,000 of working capital needed within six months), desired term, and basic security information. The interface is clean, form-based and mobile-friendly, guiding users with tooltips and worked examples.
Optional but strongly encouraged connections unlock the platform's full power:
- Companies House lookup pulls official registration, filing history, director information and accounts automatically.
- Xero or Sage integration imports the P&L, balance sheet, debtor and creditor ageing, and key financial ratios without manual re-entry.
- Open banking connection (through a regulated, authorised provider) gives access to 12–24 months of bank transactions securely, providing real payment data and live cash flow visibility (coming soon).
Step 2: AI matching and pre-qualification
The AI engine normalises the imported data, checks it against each lender's encoded criteria - ticket sizes, sector exclusions, risk appetite, collateral preferences, geographic limitations - and scores the case against available products in real time. AI-powered scoring models enhance lending decision accuracy across all asset classes.
The platform distinguishes which asset class fits best based on the business's financial profile. A company with a strong debtor book might be better served by invoice finance than a term loan; a firm with significant plant assets might qualify for asset finance at more competitive rates. The matching considers cash flow patterns, debtor book profile, existing assets and trading history.
Brokers see a ranked shortlist of suitable lenders and indicative options - for example, "three lenders likely to fund £100,000–£250,000, two to five year term, unsecured." Lenders receive only pre-qualified cases that fit their agreed parameters, dramatically reducing noise and unworkable submissions.
Step 3: Submit, collaborate and close the deal
Brokers select their preferred lenders from the shortlist, share the digital application packet and request any missing documents through the platform. In-platform messaging between broker and lender underwriters or BDMs keeps a full audit trail, avoiding the chaos of scattered email threads.
Updated offers, term sheets and conditions are uploaded and tracked centrally, so borrower and broker can see real-time status - "in underwriting", "approved subject to valuation", "funds released". Built-in regulatory compliance ensures automatic auditing and enforcement of data security standards throughout.
The final handover to the lender's own systems for documentation and drawdown happens seamlessly, with FundingSearch storing key milestones for reporting and compliance. Small business lending software enhances compliance reporting for lenders at every stage.
What makes FundingSearch different from other business lending platforms
Most solutions in the small business lending software space fall into predictable categories. FundingSearch was designed to sit outside those limitations:
- Generic loan comparison sites list products publicly but don't integrate applicant data, don't verify participants, and often generate low-quality leads that waste everyone's time.
- Single-lender portals solve the application problem for one institution but do nothing for multi-lender matching or diversified asset-class selection.
- Traditional broker email-based networks rely on personal relationships and manual rekeying - effective at small scale, but impossible to grow without proportional headcount.
Here is what sets FundingSearch apart:
- Platform, not a public marketplace – A curated network of brokers and vetted lenders. No open bidding, no uncontrolled access to deal data. Only verified participants see or submit cases, which protects data quality and builds trust between all parties.
- Broker-centric design – Workflows, reporting and integrations are built for professional commercial finance brokers and advisers, not for consumer clicks. Every feature - from case duplication to lender collaboration tools - reflects how brokers actually work, improving efficiency and enhancing productivity day to day.
- Multi-product, commercial finance focus – Seven finance asset classes on one platform, with the ability to structure blended solutions. A broker can explore a term loan plus invoice finance facility for the same client without leaving the system or rekeying data. This breadth of business finance coverage is rare in the market.
- Deep open finance integration – The combination of accounting platforms, Companies House and open banking creates a richer dataset than pure credit bureau scores alone. Lenders see normalised financials, live transaction history and verified company data, allowing businesses to present their strongest possible case.
- Transparent, subscription-based pricing for intermediaries – Brokers and lenders pay predictable fees for access and tools, not hidden commissions on each borrower's outcome. The total cost is clear, and there are no surprises. AI integration improves compliance reporting in lending software, and the subscription model aligns incentives around deal quality rather than volume of leads.
Proof that business lending software works in practice
The value of lending software is best demonstrated through measurable outcomes: time saved, approvals increased, and better fit between borrower needs and lender appetite.
- A Yorkshire-based manufacturing SME needed £400,000 in asset finance for new plant and a £150,000 invoice finance line to manage receivables. Their broker used FundingSearch to connect Xero accounting data and open banking feeds, generating a complete financial picture in minutes rather than days. The AI matching engine identified three specialist lenders with appetite for manufacturing asset finance. Time from first enquiry to approved terms dropped from four weeks to six days. Document rekeying was reduced by over 70%.
- A specialist commercial finance broker with a four-person team historically tracked around twenty lenders manually, spending hours per case gathering documents and chasing responses. After adopting FundingSearch, the broker reused company data across multiple applications, received pre-qualified matches instantly, and cut rekeying time from roughly eight hours per case to under two. Monthly case volume doubled within twelve months without adding staff. Conversion of leads to approved terms improved from around 30% to over 50%.
- A regional challenger lender focused on bridging and property finance was receiving hundreds of broker submissions by email each month - many of which were outside policy. By subscribing to FundingSearch and defining their criteria in the platform's rules engine, they received only filtered, policy-fit deal packs with structured data. Underwriter time spent on rejections fell dramatically, acceptance rates improved, and cost per approved application dropped. The lender reported greater flexibility to adjust appetite as market conditions shifted.
Automated workflows reduce loan processing time to under 24 hours for straightforward cases, and the platform's ability to handle varying loan volumes means small business lenders and larger financial institutions alike can scale without proportional operational cost increases.
Who business lending software like FundingSearch is for
- Commercial finance brokers: Manage SME funding enquiries, research lender appetite, and improve efficiency with AI matching, data reuse, and lender collaboration tools.
- Alternative and specialist lenders: Receive consistent, high-quality, pre-qualified deal flow with verified financial data, improving efficiency and reducing operational risk.
- Accountants and professional advisers: Refer clients to structured finance matching or use as a white-label tool, without needing to become a broker.
- UK SMEs seeking funding: Explore options across multiple lenders with digital financial records, no multiple hard credit checks, and free or low-cost access via a broker.
Types of business lending available on the FundingSearch platform
FundingSearch covers the main forms of UK commercial finance needed by growing SMEs, medium sized businesses and property investors, acting as a business and commercial lending platform for a wide range of use cases. Each asset class has its own data requirements, lender criteria and typical use cases. The platform's AI matching engine handles the complexity of routing each case to the right product and the right lender.
Unsecured and secured business loans
Business loans remain the most common form of SME financing. Typical use cases include working capital, stock purchases, hiring, marketing spend and equipment that does not fit a pure asset finance structure. Unsecured loans are available for businesses with strong trading performance and cash flow, while secured business loans use property or other assets as collateral.
Typical UK ranges run from £5,000 to over £1 million, with terms from six months to sixty months, though exact limits depend on individual lender policy. FundingSearch matches risk profile, sector and affordability to appropriate small business lenders, including those comfortable with early-stage but growing SMEs. The platform helps borrowers understand what flexible funding is realistically available given their financial position.
Commercial mortgages
Commercial mortgages fund owner-occupied property purchases, investment properties and mixed-use portfolios. Loan-to-value expectations, rental coverage ratios and trading performance all influence lender appetite. FundingSearch helps brokers surface lenders open to specific property types - care homes, light industrial units, retail with residential uppers, or HMOs - where mainstream banks often lack appetite or speed.
Bridging finance
Bridging loans provide short-term financing for property purchases, auction completions, refurbishments or time-sensitive opportunities where speed matters more than long-term rate. AI matching quickly identifies lenders comfortable with a specific exit strategy and timeframe. Verified data on the borrower's wider portfolio and income helps underwriters move faster on time-critical deals, and faster decisions can make the difference between securing and losing a property.
Invoice finance and factoring
Invoice finance products - factoring, confidential invoice discounting and selective invoice finance - suit B2B businesses with long payment terms that need to unlock cash tied up in receivables. FundingSearch uses accounting and ledger data via Xero or Sage to show debtor concentrations, dilution and ageing to potential lenders.
Typical facility sizes range from £50,000 to several million pounds, and sectors that commonly use invoice finance include manufacturing, distribution, recruitment and logistics. The platform's data integrations mean lenders see a clear, verified picture of the debtor book, improving their confidence and speeding up credit assessment.
Asset finance
Asset finance covers vehicles, machinery, IT equipment and other tangible assets using hire purchase and leasing structures. FundingSearch matches specific asset types, ages and values with lenders who have appetite for them. For example, a construction firm financing £250,000 of plant can be matched to a specialist asset lender within hours rather than days. New asset finance to UK SMEs reached £24.4 billion in 2025, a 4% increase on the prior year - confirming strong and growing demand in this market.
Asset-based lending (ABL)
Asset-based lending provides multi-asset revolving facilities secured against receivables, inventory, plant and sometimes property. ABL suits larger SMEs and medium sized enterprises with complex balance sheets where a single product line does not capture the full lending opportunity. Accurate, real-time financial data is critical for lender comfort: FundingSearch's open banking and accounting integrations give ABL lenders a clearer picture of asset quality and borrowing base than static PDF accounts ever could.
Trade finance
Trade finance solutions such as import and export finance, letters of credit and supply chain finance serve businesses trading internationally. FundingSearch matches trade-heavy businesses with specialist lenders comfortable with particular corridors, commodities and payment cycles. Open banking and accounting data demonstrate trade cycles, seasonality and margin stability, giving lenders the confidence to support sustainable growth in cross-border trade.
Key features to look for in business lending software
Even beyond FundingSearch, readers evaluating any business lending platform should measure it against these criteria. These key features separate tools that genuinely improve the lending process from those that simply put a digital skin on a manual workflow:
- End-to-end digital application journey – The ability to create, edit and submit applications online without printing, scanning or posting. Fast applications with online intake and automated document collection enhance borrower experience and cut days from the process.
- Open finance and open banking integrations – Support for accounting systems, Companies House and bank feeds, with clear consent flows and FCA-compliant providers. Payment data from live bank feeds is far more valuable than a three-month-old PDF statement.
- Configurable workflows and rules – Lenders should be able to tune criteria, decision thresholds and document checklists without writing code. Regulatory requirements in lending are evolving and software must adapt accordingly.
- Strong data security and compliance – Encryption in transit and at rest, role-based access controls, full audit trails and alignment with UK regulatory expectations. Compliance and audit trails are essential features for regulatory adherence in lending software.
- Broker and lender collaboration tools – Shared notes, statuses, messaging and document storage in one place, replacing fragmented email threads and lost attachments.
- Reporting and analytics – Pipeline visibility, time-to-decision metrics, sector exposure and conversion tracking. Commercial lending software supports compliance with regulatory requirements and provides the data that lenders, brokers and regulators need.
The role of AI and open banking in the future of SME lending
The direction of travel for UK business lending is clear: more data, faster decisions, less manual work. FundingSearch is positioned at the intersection of two forces - artificial intelligence and open finance - that are reshaping how capital reaches SMEs.
AI in lending goes well beyond traditional scorecards. Modern models recognise patterns in cash flow behaviour, sector cycles, repayment performance and debtor conduct, leading to more nuanced credit decisions that benefit both lenders and borrowers. AI-powered scoring models enhance lending decision accuracy, and automated workflows reduce manual errors in loan processing - cutting human error from a process where mistakes are costly.
Open banking acts as the live heartbeat of a business's finances. Instead of relying on static snapshots - a balance sheet filed months ago, a bank statement exported last quarter - lenders see up-to-date transaction data that reflects the actual rhythm of the business. As of March 2025, roughly one in five UK consumers and small businesses are active open banking users, and adoption is accelerating. The FCA published its vision for open finance in April 2026, explicitly highlighting use cases that include speeding up loan applications and improving SME access to credit.
By 2026 and beyond, SME lending is moving towards:
- Continuous eligibility monitoring rather than one-off assessments. Platforms that track open banking and accounting feeds can alert lenders and brokers when a business's position changes, enabling early refinancing or additional facilities.
- Pre-approved or pre-qualified offers based on real-time performance. Instead of applying cold, SMEs could see what business finance is available to them before they even ask, driven by live data and AI matching.
- Embedded finance, where funding options appear inside the accounting, e-commerce and invoicing platforms SMEs already use daily, rather than requiring a separate application journey.
FundingSearch is aligned with every one of these trends: deep open finance integration, AI-driven matching, and the architecture to plug into other SME tools over time. Its role as a modern loan origination marketplace reflects the digital transformation already underway in UK small business lending.
Pricing and access to FundingSearch
FundingSearch's pricing model is designed for transparency and scalability. Exact fees may evolve, but the structure is consistent:
- For brokers and advisers – Subscription-based access covers users, case volume and advanced features such as analytics and white-label options. Plans scale as the firm grows, so a solo broker and a twenty-person intermediary both find a tier that fits. There are no per-deal commissions or hidden fees that inflate costs.
- For lenders – A model combining platform access, integration support and deal flow volumes, tailored to lender size and appetite. Lenders pay for the resources and services they use, with the ability to adjust criteria and volume as market conditions shift.
- For SME borrowers – Access to the matching service is free, typically via a trusted broker or adviser. There is no obligation to accept any offer surfaced, and no upfront costs for exploring options. Allowing businesses to see their realistic funding landscape without financial commitment is a core principle.
To understand current pricing that fits your role and volume, book a demo or speak directly to the FundingSearch team.
Get started with FundingSearch
Competition for SME lending is intensifying. Lenders expect better data. Brokers need greater flexibility and efficiency. Borrowers demand speed and transparency. Early adopters of modern business lending software are already seeing measurable advantages in conversion, revenue and growth.
Here is how to take the next step:
- Brokers – Book a demo, onboard your team, connect your existing lender panel and start moving new enquiries through FundingSearch. See how AI matching and data integration can expand your capacity without expanding your headcount.
- Lenders – Speak to the FundingSearch team about encoding your criteria, integration options and how to receive high-quality, policy-fit deal flow that your underwriters can act on immediately.
- SMEs and advisers – Register interest or ask your broker or accountant to access FundingSearch on your behalf. Explore your funding options with no obligation, no upfront costs and no unnecessary credit searches.
Contact the team at fundingsearch.com to modernise your business lending and business loan origination processes. No long-term commitment. No hidden fees. Just faster, smarter, better-matched business finance.
Frequently asked questions about business lending software and FundingSearch
Common questions about our commercial lending origination software and platform
FundingSearch is a digital deal origination platform that sources, qualifies, and matches pre-vetted SME borrowers to your loan products in real time. Unlike traditional aggregators, we operate as your origination infrastructure, connecting verified borrower applications directly to your underwriting team with pre-populated financial data from Companies House, accounting software integrations (Xero, Sage, FreshBooks), and open finance APIs. This reduces time-to-decision and eliminates manual data entry across your loan book. See our commercial lending software page for further details
We focus exclusively on limited company SME borrowers (typically £5k–£50m+ deal sizes) across all commercial lending verticals: asset finance, bridging loans, commercial mortgages, invoice finance, unsecured business loans, trade finance, and asset-based lending. All borrowers complete a standardised application with verified financial data. You set borrower eligibility rules by sector, turnover, credit profile, and geography—we only send you opportunities that match your risk appetite.
Completely. You build custom lending profiles within the platform specifying: loan amount range, borrower revenue thresholds, industry sectors, geographic focus, credit score preferences, and any other underwriting criteria. The platform's matching engine only routes borrowers meeting your specifications, reducing noise and unqualified enquiries.
Most SME lending platforms are either consumer-facing marketplaces or AR networks that restrict lender independence. FundingSearch is pure infrastructure; you retain 100% of your direct lender relationships, your pricing autonomy, and your commission structure. We don't force you into networks, whitelist controls, or margin-sharing arrangements. You're a lender using a distribution layer, not a partner locked into a commercial ecosystem.
We pre-qualify. Every borrower application includes verified financial data (last 2–3 years of accounts, M.I. data where available, Companies House intelligence). Your underwriting team receives structured, data-enriched applications, not blank forms. This accelerates your assessment without removing your discretion.
We offer API-first architecture. Most lenders integrate via our REST API, allowing seamless two-way data flow: borrower leads → your CRM/LMS, underwriting decisions → our platform. We also support direct CRM integrations (Salesforce, HubSpot, Pipedrive) and offer CSV bulk import/export. Setup typically takes 2–4 weeks with our technical team.
Either. You can white-label our application journey on your domain, or borrowers can apply directly on FundingSearch.com, and we route them to you. Most lenders white-label to maintain brand control and SEO ownership, while smaller lenders benefit from FundingSearch's borrower marketing to reduce CAC.
You own the borrower relationship and data once matched. We don't retain or resell your underwriting decisions, pricing, or borrower outcomes. We're compliant with GDPR, ICO-registered, and operate under strict data processing agreements. You decide what happens to the borrower record; if declined, you manage the relationship independently.
Yes, many lenders build decisioning rules within their own systems using our data feed. Some use our structured data to trigger automated pre-approvals for low-risk profiles (e.g., high-turnover limiteds with strong financials). The platform provides the data; you control the commercial logic. FundingSearch is an API first commercial lending platform.
Not for most commercial lending products. Asset finance, bridging loans, commercial mortgages, and invoice finance are largely unregulated (provided you're not accepting deposits or offering credit to consumers). If you offer a regulated product, you should hold appropriate authorisation. We work with both regulated and non-regulated lenders. Check with your compliance team and the FCA's Handbook if uncertain.
Limited companies are business borrowers and fall outside consumer credit regulation (CONC). However, if you provide credit to individuals acting outside their business capacity, different rules apply. We work exclusively with limited company borrowers, which sidesteps CONC complexity. Confirm your lending structure with your legal team.
For business borrowing, responsible lending is about assessing repayment capacity, security, and business viability; not consumer affordability. We provide verified financial data (revenue, profit, cash flow, accounts) to support your credit decision. We don't hold lenders liable for underwriting outcomes; you retain full credit risk and commercial judgment. Our data reduces your underwriting friction, not your responsibility.
Yes. We're GDPR compliant, ICO-registered (Ref: ZB830848), and use bank-grade encryption for data in transit and at rest. All your borrower records, pricing, and product configurations are segregated and encrypted. We conduct annual security audits and pen tests.
Yes, FundingSearch is part of your blended sourcing strategy and distribution network.
All major UK SME lending verticals: Asset Finance, Bridging Loans, Commercial Mortgages, Invoice Finance, Business Loans, Unsecured Business Loans, Asset-Based Lending, Merchant Cash Advances, and Trade Finance. You can add unlimited loan products within each category; no per-product charges.
Yes. Unlimited. List 50 asset finance products with different terms, rates, and borrower profiles—no additional cost. The matching engine routes each borrower to the specific product they qualify for. This is why we're called a "commercial lending origination software" rather than a simple lead aggregator.
Lead routing + data infrastructure. We provide pre-qualified, data-enriched borrowers and structured application data (financials, Directors' details, charge information). Underwriting remains your responsibility. Some lenders layer their own decisioning rules on top of our data; others use us purely for sourcing.
You configure your product rules within the platform. You can't dynamically alter terms per borrower (that's your CRM/LMS responsibility), but you can create different product variants (e.g., "Asset Finance – Turnover £1m–£5m" vs. "Asset Finance – Turnover £5m+") with different eligibility rules and messaging to borrowers.
FundingSearch is a SaaS deal origination platform for the UK commercial finance market. It provides the digital infrastructure connecting SME borrowers, commercial finance brokers, and lenders through a single system. It is not a marketplace, an AR network, or a lead aggregator. Learn more on our lender platform page or broker software page.
A platform lender uses technology infrastructure rather than traditional distribution channels to source and originate deals. FundingSearch provides that infrastructure: structured broker submissions, verified financial data, and intelligent matching against your lending criteria. You retain full control of underwriting, pricing, and client relationships. Full details are on our commercial lending software here.
- FundingSearch is a business lending platform - specifically a deal origination platform. It is not a public marketplace and not a broker.
- It connects three parties: SMEs, independent brokers and advisers, and regulated lenders, providing the technology, data connectivity and AI matching between them.
- Commercial terms, advice and recommendations remain the responsibility of the broker and lender. FundingSearch provides the rails, not the advice.
- Key items include: company registration details, basic director information, recent management accounts, filed accounts, and bank transaction data via open banking where possible.
- Xero or Sage connections can automatically provide much of this data, reducing manual uploads and document management effort.
- Brokers can help gather and structure this data on the SME's behalf, making the process faster and less daunting.
- The platform uses encryption in transit and at rest, strict role-based access controls, and routine security testing.
- Bank data is accessed through regulated open banking providers, with explicit consent and the ability to revoke access at any time.
- Data is shared only with brokers and lenders involved in specific cases. It is never sold or exposed publicly. Built-in regulatory compliance ensures automatic auditing and enforcement of data security standards.
- Brokers and lenders typically see time-to-decision improvements within their first few dozen cases. Loan approval times can be reduced to under 24 hours for straightforward applications.
- For SMEs, using the platform can mean days instead of weeks to receive realistic options, depending on product type and complexity.
- The biggest gains come once accounting and open banking connections are in place, as repeat applications become far faster and data reuse eliminates rekeying.
Still have questions?
Our support team is ready to help you find the right financing solution
Contact usIn an AI fast paced world FundingSearch is here to deliver fintech solutions to your firm.
Open Finance is coming, the FCA says so, FundingSearch is your opportunity to reap the benefits today at a fraction of the cost of deploying your own developers. FundingSearch.com is an intelligent matching platform for UK commercial finance. The platform connects SME borrowers, commercial finance brokers, and lenders through the integration of verified financial data and intelligent matching technology. FundingSearch.com covers the full commercial finance spectrum, enabling faster, more accurate lending decisions across the UK market.
